Buying a minivan is often less about wanting a new vehicle and more about needing dependable transportation for a growing family. School runs, commuting, sports equipment, groceries, road trips and everyday responsibilities can quickly make a spacious vehicle essential. The challenge is finding financing that fits your household budget without turning a practical purchase into an expensive long-term commitment.
With minivan auto loans Canada, borrowers can compare financing through dealerships, banks, credit unions and independent lenders before choosing a structure that works for their circumstances. The Financial Consumer Agency of Canada confirms that Canadians can arrange car financing through dealerships or directly through financial institutions, giving buyers more than one financing route to consider.
For families researching family minivan financing Canada, the most important question is not simply whether a lender will approve the application. It is whether the vehicle price, interest rate, loan term, down payment and monthly payment fit comfortably within the household budget.
A lower monthly payment can sometimes hide a longer repayment period and substantially higher borrowing costs. This guide explains how minivan auto loans Canada work, what lenders consider, how to compare financing offers, how to evaluate best minivan loan rates Canada, and how to approach the purchase with greater confidence.
Understanding Minivan Auto Loans Canada
Minivan auto loans Canada are vehicle-financing arrangements used to purchase a new or used minivan. The basic structure is similar to other auto loans: a lender provides financing toward the vehicle purchase, and the borrower repays the principal plus interest over an agreed term. What makes minivan financing particularly important is the size of the purchase. A family-oriented minivan can represent a significant financial commitment, so even a modest difference in interest rate can affect the total amount repaid.
When comparing family minivan financing Canada, borrowers should look beyond the payment shown in an advertisement. The amount financed, interest rate, term, payment frequency, lender fees and optional products can all influence the final cost. Canada’s Financial Consumer Agency recommends comparing financing options and considering the complete cost of borrowing rather than focusing exclusively on the monthly payment. minivan auto loans Canada
A borrower may obtain financing through a dealership, bank, credit union or independent finance company. Dealership financing can be convenient because the financing process is handled alongside the vehicle purchase, while direct financing can give a buyer another offer against which to compare the dealer’s proposal.
The right option depends on the borrower’s financial profile, the vehicle and the terms actually available. There is no universal lender or financing channel that is automatically cheapest for every Canadian family. minivan auto loans Canada
Why Families Choose Minivan Financing
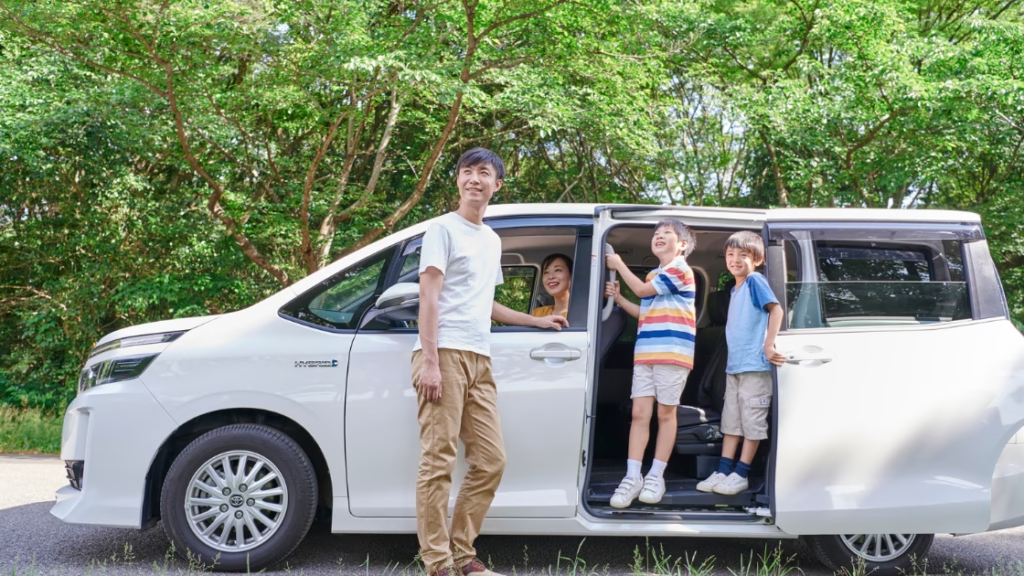
Family minivan financing Canada can make a larger family vehicle accessible without requiring the entire purchase price to be paid upfront. Minivans are particularly useful for households that regularly transport several passengers because they generally prioritize seating capacity, interior flexibility and cargo space. For families who need a practical vehicle for several years, financing may also allow them to purchase a vehicle that better matches their long-term transportation needs instead of choosing a smaller vehicle solely because its upfront price is lower.
When evaluating 3-row vehicle car loans Canada, affordability should be considered alongside practicality. A cheaper vehicle is not necessarily cheaper to own if it creates limitations that force another vehicle purchase sooner than expected.
Conversely, choosing the largest or most expensive minivan available simply because financing makes the payment appear manageable can create unnecessary financial pressure. The strongest approach is to determine the household’s sustainable transportation budget first and then select a vehicle and financing structure that remain within it.
How Lenders Evaluate Minivan Financing Applications
Approval for minivan auto loans Canada depends on the lender’s underwriting process and the applicant’s overall financial circumstances. Credit history is important, but it is not the only factor.
Lenders may also consider income, employment or income stability, existing debts, requested loan amount, down payment, vehicle information and the applicant’s ability to manage the proposed payments. Different lenders can evaluate the same borrower differently, which is one reason comparing financing options can be valuable.
For family minivan financing Canada, borrowers should be prepared to provide accurate personal and financial information. Typical documentation can include government-issued identification, proof of residence, employment or income information and vehicle details. Self-employed or variable-income applicants may be asked for additional documentation. Providing complete information from the beginning can reduce avoidable delays and make it easier for a lender to assess the application.
Your credit report deserves attention before applying. The Government of Canada says Canadians can access their credit reports online for free through Canada’s two main credit bureaus, Equifax and TransUnion, and checking your own report does not affect your credit rating. Reviewing both reports can help identify inaccurate information before it becomes an obstacle during a financing application.
Step-by-Step Guide to Getting a Minivan Loan
Step 1: Establish Your Family Vehicle Budget
Before looking at minivan auto loans Canada, establish the maximum amount your household can reasonably allocate toward transportation each month. Consider more than the loan payment. Insurance, fuel, maintenance, registration, winter tires, parking and unexpected repairs can all affect the true cost of ownership. A financing payment that technically fits a budget can still become uncomfortable once these additional expenses are included.
Step 2: Check Your Credit Profile
Your credit profile can influence both approval and pricing. For family minivan financing Canada, obtain your credit reports before submitting applications and check for incorrect balances, accounts that do not belong to you or outdated information. Canada.ca recommends checking both Equifax and TransUnion because the information held by the two bureaus can differ.
Step 3: Determine Your Down Payment
A down payment reduces the amount that must be financed. For 3-row vehicle car loans Canada, even a moderate down payment can reduce the principal and may improve the overall financing structure. However, a down payment should not automatically consume every dollar of available savings. Keeping an emergency reserve can be more important than reducing the loan by a relatively small amount.
Step 4: Compare Actual Financing Offers
When searching for best minivan loan rates Canada, compare actual offers rather than relying exclusively on advertised rates. Ask for the interest rate, amount financed, term, payment frequency, total borrowing cost and total amount repaid. A lender offering a slightly higher monthly payment but a significantly shorter term could potentially cost less overall.
Step 5: Review the Vehicle Separately From the Financing
A strong financing offer cannot turn an overpriced vehicle into a good purchase. Research the minivan’s market value, condition, mileage and expected ownership costs independently of the financing discussion. Separating the vehicle negotiation from the financing decision can make it easier to identify the true cost of the transaction.
Step 6: Read the Contract Before Signing
Before accepting minivan auto loans Canada, review every important number. Confirm the amount financed, interest rate, term, payment schedule, total borrowing cost and any optional products. If a dealer offers additional warranties, protection products or other services, make sure you understand whether they are optional and how they affect the amount financed.
Minivan Loan Eligibility and Requirements
Eligibility for family minivan financing Canada varies between lenders, so there is no single credit-score threshold or income requirement that guarantees approval everywhere. A lender may evaluate credit history, income, employment stability, debt obligations, vehicle value and repayment capacity together. A borrower with a stronger financial profile may have access to more competitive financing, while another borrower may still qualify through a lender with different underwriting criteria.
Common documentation for _minivan auto loans Canada may include:
- Government-issued identification
- Proof of Canadian residence
- Employment or income information
- Recent pay documentation where applicable
- Banking information where legitimately required
- Vehicle details or purchase information
- Down-payment information
- Authorization for the lender to assess credit
Applicants with variable or self-employed income should be prepared to explain how their income is generated and provide appropriate supporting documentation. Accuracy matters. Inconsistent information between an application and supporting documents can create unnecessary delays.
Understanding Minivan Loan Rates and Total Cost
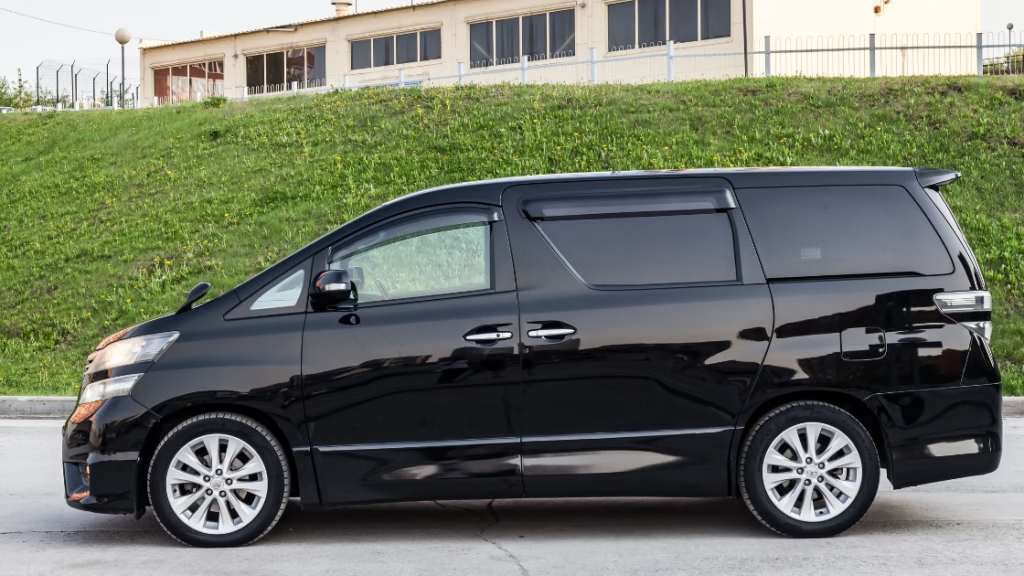
The phrase best minivan loan rates Canada should never be interpreted as one universal interest rate available to every borrower.
Auto-loan pricing varies according to the borrower, lender, vehicle, term and financing structure. Bank of Canada data provides useful market context: its July 2026 statistics showed an average rate of 6.66% for newly advanced auto loans among chartered banks, while the average rate on outstanding auto-loan balances was 6.83%. These figures are market-level statistics, not guaranteed offers for an individual applicant.
The following examples are illustrative rather than advertised rates:
| Amount Financed | Illustrative Rate | Term | Approx. Monthly Payment | Approx. Total Interest |
|---|---|---|---|---|
| $30,000 | 6.66% | 60 months | $589 | $5,340 |
| $35,000 | 6.66% | 60 months | $688 | $6,280 |
| $35,000 | 8.99% | 60 months | $726 | $8,560 |
| $35,000 | 11.99% | 72 months | $684 | $14,250 |
Illustrative calculations only. Actual payments, interest and total borrowing costs depend on the lender, borrower, taxes, fees, payment schedule and contract terms.
The table demonstrates why minivan auto loans Canada should be evaluated over the entire repayment period. Extending a loan can make the monthly payment easier to manage, but it can also increase the amount of interest paid. The appropriate term is therefore not necessarily the longest term a lender will approve. It is the term that balances an affordable payment with a reasonable total borrowing cost.
New vs. Used Minivan Financing
For buyers comparing affordable minivan deals Canada, a used minivan may offer a lower purchase price than a comparable newer model. However, the financing decision should consider vehicle age, mileage, condition and expected maintenance requirements. A lower purchase price can be attractive, but an older vehicle may have higher repair needs or different financing availability.
Newer minivans can have advantages such as newer safety technology, warranty coverage and lower initial maintenance risk. However, they can also require a larger loan. When evaluating family minivan financing Canada, compare the complete ownership equation rather than focusing only on the sticker price.
A useful comparison is to calculate the purchase price, down payment, amount financed, interest, estimated insurance, fuel and expected maintenance for each option. This can reveal whether the lower-priced vehicle actually produces meaningful savings over the period you expect to own it.
Banks vs. Lenders vs. Brokers
Canadian consumers searching for best minivan loan rates Canada may encounter several financing channels. Banks can be attractive for borrowers with established financial relationships and strong credit. Credit unions may have their own membership and underwriting requirements. Independent finance companies can provide another financing route, particularly for applicants who do not fit conventional lending criteria.
| Financing Channel | Potential Advantage | What to Compare |
|---|---|---|
| Bank | Established financial relationship | Rate, term and eligibility |
| Credit Union | Alternative underwriting approach | Membership, rate and conditions |
| Independent Lender | Potentially broader borrower profiles | Interest rate, fees and total cost |
| Dealer Financing | Convenient one-stop process | Rate, lender, commission disclosure and total cost |
| Financing Broker | May access multiple lending sources | Lender options, compensation and final terms |
The Financial Consumer Agency of Canada confirms that vehicle financing may be obtained through dealerships, banks, credit unions and independent finance companies.
Dealership financing can be convenient, but borrowers should understand how the process works. In Ontario, OMVIC notes that dealers may receive compensation from lenders for arranging financing and advises consumers to check financing disclosures and ensure available rates have been presented.
Canadian Case Study: A Growing Family
Consider a household that needs a minivan because two parents regularly transport three children, sports equipment and groceries. They find a vehicle requiring $35,000 of financing and initially focus on keeping the payment as low as possible. The first offer uses a longer term, producing a lower monthly payment but substantially increasing the total interest.
Instead of automatically choosing the lowest payment, the family compares the full cost of family minivan financing Canada. They increase the down payment slightly while keeping an emergency reserve, select a manageable term and compare another financing offer. The resulting payment is somewhat higher, but the household saves on total interest and pays off the vehicle sooner.
The lesson is simple: 3-row vehicle car loans Canada should be evaluated according to household affordability and total borrowing cost, not merely the smallest advertised monthly payment.
Canadian Case Study: Choosing an Affordable Used Minivan
Another borrower wants one of the affordable minivan deals Canada available on the used market. Instead of selecting the cheapest vehicle available, the borrower compares several vehicles based on purchase price, mileage, condition, expected maintenance and financing terms.
A slightly more expensive minivan has better documented maintenance history and qualifies for a more favourable financing structure. Although the purchase price is higher, the borrower expects fewer immediate repairs and accepts a shorter financing term. The decision demonstrates why vehicle price and financing cost should be analyzed together.
A used vehicle should also be researched carefully before purchase. Ontario’s vehicle regulator, OMVIC, recommends checking vehicle history and value and emphasizes the importance of understanding financing terms, cost of borrowing, interest rate and payment schedule.
How to Improve Your Minivan Loan Approval Chances
Borrowers looking for minivan auto loans Canada can improve their preparation before applying. First, make sure the application information is accurate and complete. Second, review credit reports and correct errors where necessary. Third, understand how much monthly payment the household can genuinely afford. Fourth, keep documentation organized so the lender can verify income and other information efficiently.
For family minivan financing Canada, avoiding unnecessary last-minute financial changes can also help maintain a clean application profile. Do not make major new credit commitments immediately before applying unless necessary. Avoid providing inconsistent income information or applying without knowing the approximate vehicle price you can afford.
A realistic application is stronger than an overly ambitious one. If the requested financing amount is substantially beyond the household’s comfortable budget, approval alone does not make the purchase financially sensible.
Mistakes to Avoid With Minivan Financing
One of the most common mistakes with minivan auto loans Canada is choosing a vehicle based entirely on the monthly payment. A payment can look affordable because the repayment period is unusually long. Always calculate the total amount you will repay.
Another mistake is assuming the advertised rate is automatically available to every borrower. Financing offers are often conditional on borrower qualifications, vehicle requirements and other terms. Compare the actual offer presented to you.
A third mistake is overlooking optional products. Extended warranties, protection packages and other products may increase the amount financed. Read the contract carefully and decide whether each product provides enough value to justify its cost.
A fourth mistake is failing to compare financing sources. The Financial Consumer Agency of Canada specifically recommends shopping around for auto financing rather than automatically accepting the first option presented.
Finally, avoid rushing because you feel pressure to buy immediately. A minivan is a major financial commitment. Taking additional time to compare the vehicle, financing and total cost can protect your household from an unnecessarily expensive decision.
Protect Yourself When Buying a Minivan
When evaluating affordable minivan deals Canada, the advertised vehicle price should be examined separately from financing. Provincial consumer-protection rules differ, so buyers should understand the rules applicable where they purchase the vehicle.
For example, Ontario requires registered dealers to follow all-in pricing rules. OMVIC states that advertised vehicle prices must include the fees and charges the dealer intends to collect, with HST and licensing generally allowed to be excluded when properly disclosed.
Ontario consumers should also understand financing disclosures. OMVIC explains that financing advertisements can require disclosure of APR, term, cash price and cost of borrowing, depending on the advertisement.
Regardless of province, buyers should request a complete written breakdown of the transaction and review the contract before signing.
Frequently Asked Questions About Minivan Auto Loans Canada
1. What are minivan auto loans Canada?
Minivan auto loans Canada are financing arrangements used by Canadian consumers to purchase new or used minivans. The borrower generally repays the amount financed plus interest according to a scheduled payment plan. Financing can be arranged through a dealership, bank, credit union or independent finance company. The best structure depends on the applicant’s credit profile, income, vehicle, down payment, requested amount and repayment capacity. Rather than selecting financing based only on the monthly payment, compare the interest rate, term, total interest, fees and total amount repaid.
2. How can I find the best minivan loan rates Canada?
To find best minivan loan rates Canada, compare actual financing offers instead of relying only on advertised rates. Request the same basic information from each financing source, including the amount financed, interest rate, term, payment frequency and total borrowing cost. Your credit history and financial circumstances can affect the rate you receive, so an advertised rate is not necessarily your personalized offer. The Bank of Canada publishes aggregate auto-loan statistics that can provide useful market context, but those statistics should not be treated as guaranteed individual rates.
3. Can I get family minivan financing Canada with a less-than-perfect credit history?
Family minivan financing Canada may still be available to borrowers whose credit history is not ideal, although approval and pricing depend on the lender and overall application. A lender may consider income, existing debts, repayment history, down payment, vehicle characteristics and other information in addition to the credit score. Borrowers with weaker credit should focus particularly on affordability and total borrowing cost because a higher interest rate can materially increase the cost of the vehicle. Reviewing your credit reports before applying can also help identify errors that may be affecting your financing profile.
4. Is a 3-row vehicle car loan more expensive?
A 3-row vehicle car loans Canada application is not automatically more expensive simply because the vehicle has three rows. The amount you borrow, vehicle price, lender, credit profile, interest rate and loan term generally have a much greater effect on financing cost. However, larger vehicles may have higher purchase prices, which can increase the amount financed. The best approach is to compare the complete financing structure and ensure the vehicle meets your family’s needs without stretching the household budget.
5. Should I buy a new or used minivan?
When comparing affordable minivan deals Canada, neither a new nor used vehicle is automatically the better financial choice. A new minivan may provide newer technology, warranty coverage and predictable early ownership costs, while a used minivan can reduce the purchase price. The right choice depends on vehicle condition, financing terms, depreciation, maintenance expectations and how long you intend to keep it. Compare the total expected ownership cost rather than simply comparing purchase prices.
6. Does a longer minivan loan lower my monthly payment?
A longer term can reduce the required payment because the amount borrowed is spread over more payments. However, minivan auto loans Canada with longer terms can result in more interest being paid over the life of the loan when other factors remain comparable. A lower monthly payment therefore does not necessarily mean a cheaper loan. Before choosing a longer term, calculate the total amount repaid and consider how long you expect to keep the vehicle.
7. Should I check my credit report before applying?
Yes. For family minivan financing Canada, reviewing your credit reports before applying can help you identify inaccurate information or suspicious accounts. Canada.ca states that Canadians can obtain free credit reports online from Equifax and TransUnion, and checking your own report does not affect your credit rating. If you find an error, correcting it before applying may help prevent avoidable financing problems.
8. Should I accept dealer financing?
Dealer financing can be convenient, but borrowers searching for best minivan loan rates Canada should still compare the dealer’s offer against other available options. Canada.ca notes that dealerships can arrange financing with manufacturer financing divisions, banks, credit unions and independent finance companies. In Ontario, OMVIC also advises consumers to understand that dealers can receive compensation from lenders for arranging loans. Review the financing disclosures, compare the complete cost and make sure you understand the lender, interest rate and repayment terms before signing.
Final Checklist Before Signing Your Minivan Loan
Before accepting minivan auto loans Canada, confirm these points:
- The vehicle fits your actual transportation needs.
- The purchase price fits your overall budget.
- The down payment does not eliminate your emergency savings.
- You know the exact interest rate.
- You understand the complete loan term.
- You know the payment amount and frequency.
- You have calculated the total amount repaid.
- You understand all fees and optional products.
- You have reviewed your credit information.
- You have compared more than one financing option where practical.
- You have read the agreement before signing.
- You are comfortable with the payment even if household expenses increase.
Conclusion: Choose the Minivan Financing That Fits Your Family
Choosing minivan auto loans Canada should be about more than securing approval. The strongest financing decision balances vehicle practicality, purchase price, interest rate, loan term, monthly affordability and total borrowing cost. Families should begin with a realistic transportation budget, research the vehicle independently, review their credit information and compare financing options before committing.
For borrowers comparing family minivan financing Canada, the goal should not simply be the lowest possible payment. It should be a sustainable payment attached to a financing structure that makes sense over the entire ownership period. Similarly, searching for best minivan loan rates Canada should mean comparing real financing offers rather than chasing an advertised number that may not apply to your circumstances.
If you are considering a minivan and want to explore your financing options, Quick Auto Loan Approvals provides an online starting point for Canadian vehicle financing. You can begin by reviewing your options through Quick Auto Loan Approvals and preparing the information needed for a financing assessment. A well-prepared application, realistic budget and careful comparison can help you move toward family transportation with greater financial confidence.
Internal Links for QuickApprovals.ca
- https://quickapprovals.ca/
- https://quickapprovals.ca/digital-car-loan-platforms-canada/
- https://quickapprovals.ca/personalized-car-loan-offers-canada/
- https://quickapprovals.ca/fast-car-loan-funding-canada/
- https://quickapprovals.ca/online-car-loan-approval-process-canada/
- https://quickapprovals.ca/low-interest-used-car-loans-canada/
Authority Outbound References
- https://www.canada.ca/en/financial-consumer-agency/services/loans/financing-car.html
- https://www.canada.ca/en/financial-consumer-agency/services/loans/financing-car/financing-options.html
- https://www.canada.ca/en/financial-consumer-agency/services/credit-reports-score/order-credit-report.html
- https://www.bankofcanada.ca/rates/banking-and-financial-statistics/interest-rates-for-new-and-existing-lending-by-chartered-banks/
- https://www.omvic.ca/buying/
- https://www.omvic.ca/buying/your-rights/financing-disclosures/