Buying a hybrid can change the economics of driving, but the purchase price still has to fit your finances. For many Canadians, the challenge is not deciding whether a hybrid vehicle makes sense—it is finding financing that balances the vehicle price, interest rate, loan term, down payment and long-term ownership costs.
With hybrid car financing Canada, you can finance a conventional hybrid or an eligible plug-in hybrid through several channels, including banks, credit unions, dealerships, independent lenders and financing brokers. The right structure depends on your credit profile, income, debt obligations, vehicle, down payment and the lender’s underwriting policies. Canada’s Financial Consumer Agency recommends comparing financing offers based on the full cost of borrowing rather than focusing only on the monthly payment.
In this guide, you will learn how hybrid vehicle auto loans Canada work, what affects plug-in hybrid loan rates Canada, which documents lenders may request, how to compare financing sources, and how to reduce avoidable borrowing costs before signing a contract. hybrid car financing Canada
What Is Hybrid Car Financing in Canada?
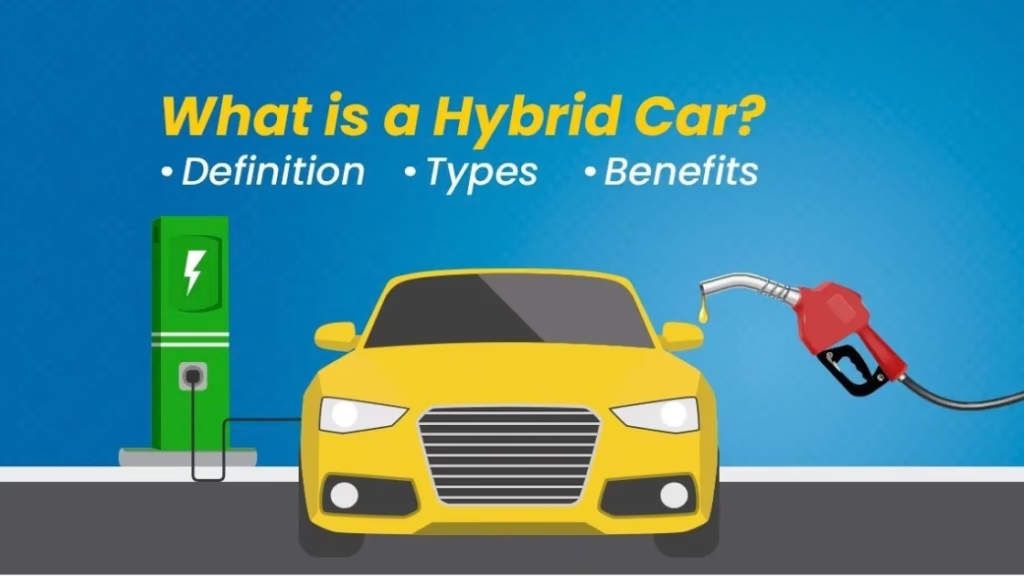
Hybrid car financing Canada is an auto loan used to purchase a vehicle that combines an internal-combustion engine with electric propulsion. Conventional hybrids generally recharge their battery through regenerative braking and the vehicle’s engine, while plug-in hybrids can also be charged externally.
From a financing perspective, a hybrid is generally treated as a vehicle purchase rather than a completely separate category of borrowing. A lender may evaluate the applicant’s credit history, income, existing obligations, requested loan amount, vehicle characteristics and repayment capacity. The fact that a vehicle is a hybrid does not automatically guarantee a lower interest rate. hybrid car financing Canada
That distinction matters when comparing eco friendly car financing Canada options. A borrower may see a manufacturer promotion for a particular hybrid while another lender offers a different rate or term. The advertised payment may also exclude taxes, fees, optional products or other costs. The Financial Consumer Agency of Canada specifically recommends comparing the interest rate, financing fees, amount financed, payment schedule and loan length
For that reason, the most useful question is not simply, “What is the hybrid rate?” It is, “What will this specific vehicle and financing agreement cost me from the first payment to the final payment?” hybrid car financing Canada
How Hybrid Vehicle Auto Loans Work
Choosing the Vehicle and Financing Amount
The foundation of hybrid vehicle auto loans Canada is the amount you actually need to borrow. Start with the negotiated vehicle price and account for applicable taxes, registration-related costs, fees and optional products before subtracting your down payment or eligible trade-in value.
For example, suppose a hybrid has an agreed purchase price of $32,000 and you provide $5,000 toward the purchase. The amount financed may be substantially lower than the vehicle’s advertised price, although the final financed balance depends on taxes, fees and the transaction structure. hybrid vehicle auto loans Canada
This is also where hybrid car financing Canada becomes a budgeting exercise rather than simply a loan application. A smaller financed balance generally means less interest over the life of the loan, assuming the rate and term remain comparable.
Conventional Hybrid vs Plug-In Hybrid Financing
A conventional hybrid and a plug-in hybrid can have different purchase prices, equipment levels and incentive eligibility. A plug-in model may have a larger battery and charging capability, while a conventional hybrid may be simpler for someone who does not have convenient access to charging. hybrid vehicle auto loans Canada
When comparing plug-in hybrid loan rates Canada, do not assume that the vehicle’s environmental credentials automatically determine your financing rate. The lender can still consider your credit history, income, debts, loan amount and vehicle details.
Government incentive programs also need to be checked carefully. Canada’s current Electric Vehicle Affordability Program includes eligible plug-in hybrid vehicles, with the exact incentive depending on the vehicle and transaction. The federal program lists a 2026 incentive of up to $2,500 for eligible PHEVs in qualifying circumstances, while the broader program can provide up to $5,000 for qualifying light-duty EVs. Eligibility and amounts should be verified for the exact vehicle before they are included in your financing calculations.
What Determines Your Hybrid Loan Rate?
Credit Profile and Repayment History
Your credit history is one part of the lender’s risk assessment when you apply for hybrid car financing Canada. A strong history of managing credit can support access to more competitive financing, while previous missed payments, collections, high balances or limited credit history can affect the terms available to you. plug-in hybrid loan rates Canada
However, there is no single Canadian credit-score threshold that guarantees a particular hybrid loan rate. Each lender has its own policies, and the complete application matters.
Income and Existing Debt
Income matters because the lender needs to determine whether the proposed payment is affordable alongside your existing obligations. Someone earning a stable salary may present their situation differently from a self-employed applicant, contract worker or person with variable income.
For hybrid vehicle auto loans Canada, prepare documentation that demonstrates your current financial position. Depending on the lender, this may include pay stubs, employment information, bank statements, tax documents or other proof of income.
Vehicle Price and Loan Term
The amount you borrow and the length of the loan can materially affect your total cost. A longer term usually reduces the scheduled payment but increases the period during which interest accumulates. The Financial Consumer Agency of Canada illustrates this principle with car-loan examples and warns that longer terms can result in substantially greater total borrowing costs.
This is particularly important when evaluating best hybrid loan deals Canada. A loan with the smallest monthly payment is not necessarily the least expensive financing arrangement.
Hybrid Car Financing Rates: Cost Breakdown
There is no universal rate that applies to every Canadian hybrid buyer. Actual offers can vary according to the borrower, vehicle, lender, promotional program and transaction structure.
Canada’s broader interest-rate environment provides useful context. On September 2, 2026, the Bank of Canada maintained its target for the overnight rate at 2.25%. That policy rate influences broader financial conditions, but it is not the consumer’s auto-loan rate.
The following examples are illustrative calculations, not advertised or guaranteed rates:
| Illustrative Rate | Amount Financed | Term | Approx. Monthly Payment | Approx. Total Interest |
|---|---|---|---|---|
| 4.99% | $30,000 | 60 months | $566 | $3,960 |
| 6.99% | $30,000 | 60 months | $594 | $5,634 |
| 8.99% | $30,000 | 60 months | $623 | $7,356 |
| 11.99% | $30,000 | 60 months | $667 | $10,031 |
These figures demonstrate why comparing plug-in hybrid loan rates Canada requires looking beyond the payment. A difference of several percentage points can translate into thousands of dollars over five years.
Your actual payment can also change because of taxes, fees, down payment, trade-in value, optional products and the precise loan structure. Always use the final written financing disclosure rather than an informal payment estimate.
How to Compare Hybrid Financing Options
Banks
Banks can be a natural starting point for borrowers with established credit and an existing financial relationship. You may apply directly to your financial institution rather than arranging financing exclusively through a dealership.
The Financial Consumer Agency of Canada confirms that car financing can be obtained through financial institutions as well as dealerships. It also notes that having an existing relationship with a financial institution may sometimes provide room to negotiate financing terms.
Credit Unions
Credit unions are another financing channel worth comparing. Their lending policies, membership requirements and pricing structures can differ from those of major banks.
For hybrid car financing Canada, comparing a credit-union offer with a dealership or other lender can help you understand whether the proposed rate and term are competitive for your particular financial situation.
Dealership Financing
Dealership financing can be convenient because the finance process is integrated into the vehicle purchase. Dealers may arrange financing through a manufacturer’s finance division, bank, credit union or independent finance company.
However, convenience should not replace comparison. FCAC recommends obtaining quotes from multiple dealers and lenders and comparing the full financing details.
Independent Lenders and Brokers
Independent financing sources can provide another route, particularly when a borrower’s credit or income situation does not fit conventional lending criteria. eco friendly car financing Canada
For eco friendly car financing Canada, the important issue is still the final agreement: interest rate, total amount financed, fees, term, payment schedule and repayment conditions.
| Financing Source | Potential Advantage | Important Comparison Point |
|---|---|---|
| Bank | Existing relationship may help | Eligibility and underwriting |
| Credit Union | Different lending policies | Membership and terms |
| Dealership | Convenient one-stop process | Compare lender offers |
| Independent Lender | Alternative underwriting | Rate and fees |
| Broker | Can present multiple financing options | Understand the final lender and contract |
No financing source automatically provides the right deal for every borrower. Compare the actual offers available to you. eco friendly car financing Canada
Step-by-Step Guide to Getting Hybrid Car Financing Canada
Step 1: Establish Your Realistic Budget
Before looking at vehicles, calculate how much you can comfortably allocate to the purchase. Include the vehicle payment, insurance, fuel, charging costs where applicable, maintenance and other recurring transportation expenses. eco friendly car financing Canada
Your goal with hybrid car financing Canada should be sustainable ownership, not simply obtaining the largest possible approval.
Step 2: Review Your Credit
Check your credit information before applying. Look for incorrect information, unfamiliar accounts or other issues that may need attention.
A clean and accurate credit file can make it easier for lenders to assess your application. best hybrid loan deals Canada
Step 3: Decide on Your Down Payment
A down payment reduces the amount that must be financed. It can therefore reduce the payment and, depending on the loan structure, reduce total interest. best hybrid loan deals Canada
Do not empty your emergency savings simply to increase the down payment. A financing decision should leave you with enough financial flexibility for unexpected expenses.
Step 4: Compare Financing Before Signing
Obtain financing information from more than one source when practical. Compare the rate, term, fees, amount financed, payment frequency and total repayment.
This is the stage where you can identify genuine best hybrid loan deals Canada opportunities without relying on promotional language alone.
Step 5: Negotiate the Vehicle Price
Keep the vehicle price and financing discussion clear. A lower payment can sometimes be achieved by extending the term rather than reducing the actual cost.
FCAC advises consumers to compare the vehicle price and total financing cost rather than focusing solely on the monthly payment.
Step 6: Verify Incentives
If the vehicle qualifies for an applicable federal or provincial incentive, confirm the eligibility rules and transaction requirements before counting the incentive as part of your budget.
Do not assume every hybrid qualifies. The federal Electric Vehicle Affordability Program has specific vehicle and transaction conditions, and its current vehicle list identifies qualifying models and incentive amounts.
Step 7: Review the Final Contract
Before signing, verify the interest rate, amount financed, payment schedule, term, fees, optional products and total cost.
For federally regulated financial institutions, consumer-protection rules require disclosure of important loan information, and FCAC recommends reading the disclosure carefully before finalizing the agreement.
Hybrid Loan Eligibility and Requirements
Basic Application Information
Most hybrid vehicle auto loans Canada applications require information such as:
- Government-issued identification
- Residential address
- Employment information
- Income details
- Existing financial obligations
- Credit information
- Vehicle details
- Down-payment information, where applicable
Additional documentation may be requested depending on the lender and applicant.
Income Documentation
Employees may be asked for recent pay information or employment verification. Self-employed or contract applicants may need additional records demonstrating income consistency.
The objective is to make the application easy for the lender to understand. Accurate documentation is more useful than submitting a large quantity of inconsistent paperwork.
Credit History
A weak credit history does not necessarily mean there is no financing route, but it can affect the cost and conditions of borrowing. If your credit profile is less established, compare offers particularly carefully because a higher rate can materially increase the total cost of hybrid car financing Canada.
Canadian Case Study: Strong Credit Buyer
Consider a hypothetical Ontario buyer with stable employment, established credit and $6,000 available for a down payment. The buyer identifies a $35,000 hybrid and compares three financing offers before signing.
Instead of choosing the offer with the lowest advertised monthly payment, the buyer compares the amount financed, interest rate and term. One offer has a longer term and a lower payment, while another has a higher payment but materially less total interest.
The buyer chooses based on the complete cost structure. This illustrates why best hybrid loan deals Canada should be evaluated using total borrowing cost rather than monthly payment alone.
Canadian Case Study: Variable-Income Borrower
Now consider a hypothetical self-employed Canadian whose income changes from month to month. The borrower wants a plug-in hybrid but does not have conventional payroll documentation.
The borrower prepares tax records, bank statements and other income documentation before applying. Instead of assuming that a variable income profile automatically prevents approval, the borrower presents a complete financial picture and compares lenders.
For plug-in hybrid loan rates Canada, the final offer may differ from that available to a salaried borrower because underwriting considers the applicant’s overall risk profile.
Canadian Case Study: Longer-Term Financing
Suppose another borrower wants to keep the monthly payment low and considers a seven-year loan. The lower scheduled payment may improve short-term cash flow, but the borrower needs to consider the additional interest and the possibility of owing more than the vehicle is worth during part of the repayment period.
FCAC specifically warns about long-term vehicle loans because borrowers can find themselves owing more than the vehicle is worth, particularly if they trade the vehicle before the loan is paid off.
For eco friendly car financing Canada, the same principle applies: a hybrid’s fuel efficiency does not eliminate the financial consequences of an unnecessarily long loan.
How to Accelerate Your Hybrid Loan Approval
Prepare Documentation Before Applying
Organize identification, income information, employment details and residence documentation before beginning the application.
A complete application can make the review process more straightforward.
Choose an Affordable Vehicle
The vehicle itself affects the amount you need to finance. Selecting a model that fits your budget can make the application more manageable.
Do not treat the maximum amount a lender is willing to finance as the amount you should necessarily spend.
Reduce Unnecessary Debt
Existing monthly obligations affect your overall affordability. Paying down certain debts before applying may improve your financial position, provided doing so does not eliminate necessary cash reserves.
Keep Information Consistent
Make sure the income, employment, residence and debt information on your application is accurate and consistent with your supporting documents.
Compare Before Signing
The fastest approval is not automatically the cheapest financing. Use the approval process to obtain clear terms and then compare them.
Critical Mistakes to Avoid
Focusing Only on the Monthly Payment
A lower payment can result from a longer repayment term. The total amount paid may therefore be considerably higher. FCAC recommends comparing the full cost of financing, including the term and total amount financed.
Assuming Hybrid Financing Is Automatically Cheaper
Fuel savings and financing costs are separate calculations. A hybrid may reduce fuel consumption while still carrying a higher purchase price or financing cost.
Evaluate both sides of the equation.
Ignoring the Vehicle’s Total Ownership Cost
Your budget should account for insurance, maintenance, fuel, charging where applicable, registration and other ownership expenses—not just the loan payment.
Accepting the First Financing Offer
A dealership, bank, credit union and independent lender may have different offers. Comparing them can reveal differences in rates, terms and fees.
Extending the Loan Without Understanding the Consequences
A longer loan may make the monthly payment easier to manage, but it can increase interest costs and prolong the period before the loan balance falls below the vehicle’s value.
Assuming Every Incentive Applies
Government incentive eligibility changes and depends on the specific vehicle and transaction. Check current official information before relying on an incentive in your affordability calculations.
FAQs About Hybrid Car Financing Canada
1. Can I finance a hybrid vehicle through a regular car loan?
Yes. hybrid car financing Canada can generally be arranged through the same broad financing channels used for other vehicles, including banks, credit unions, dealerships and independent finance companies. The exact approval criteria and rate depend on the lender and your application. The vehicle’s hybrid status does not by itself guarantee approval or a particular rate. Compare the amount financed, interest rate, term, fees and total repayment before signing.
2. Are plug-in hybrids eligible for Canadian government incentives?
Some plug-in hybrids can qualify under Canada’s current Electric Vehicle Affordability Program, but eligibility depends on the specific vehicle and transaction. Canada’s 2026 vehicle list includes qualifying PHEVs, including certain models with an incentive amount of $2,500 for purchase or a 48-month lease. Eligibility should always be verified using the current federal vehicle list before you include an incentive in your budget.
3. Will a hybrid automatically get a lower interest rate?
No. plug-in hybrid loan rates Canada are not determined solely by fuel type. A lender may consider your credit history, income, existing debts, vehicle price, loan amount, term and other underwriting factors. Manufacturer financing promotions can also differ from standard financing. The best way to understand your actual cost is to compare written offers for the exact vehicle and amount you intend to finance.
4. Is a longer loan term better for hybrid financing?
A longer term can reduce the scheduled monthly payment, but it normally means making payments for a longer period and can increase total interest. It can also increase the risk of negative equity if the vehicle depreciates faster than the loan balance declines. FCAC advises Canadians to understand these risks before choosing long-term vehicle financing.
5. Can someone with imperfect credit finance a hybrid?
Potentially, yes. Different lenders use different underwriting criteria, so there is no universal credit-score cutoff that applies to every application. However, weaker credit can result in fewer options or a higher borrowing cost. If your credit is less established, focus particularly on affordability, documentation and comparing the complete financing agreement rather than accepting the first available offer.
6. Should I get financing before choosing the hybrid?
Obtaining financing information before negotiating the vehicle can help you establish a realistic budget. It can also make it easier to compare a dealer’s financing offer against another source. However, pre-approval should not be treated as a reason to spend the maximum amount available. The final vehicle price, fees, taxes, financing structure and lender conditions still need to be reviewed.
7. How much should I put down on a hybrid?
There is no single down-payment amount that is appropriate for every buyer. A larger down payment reduces the amount financed and can reduce the total interest paid when other terms remain comparable. However, using all your available savings can leave you financially exposed. A sensible approach is to balance the down payment against emergency savings, other debts and the complete ownership cost.
8. How can I compare the best hybrid loan deals?
Start by comparing the actual written offers rather than advertisements. For best hybrid loan deals Canada, review the interest rate, amount financed, term, payment schedule, fees, optional products and total repayment. Also compare the vehicle’s negotiated price and applicable incentives. A financing offer should be evaluated as part of the entire purchase rather than as an isolated monthly payment.
Final Thoughts on Hybrid Car Financing Canada
A hybrid can offer a different balance of fuel efficiency, electric driving and conventional-engine flexibility, but the financial benefits depend on the complete purchase structure. The strongest financing decision is built around affordability, transparent terms and careful comparison—not simply the lowest advertised payment.
When evaluating hybrid car financing Canada, compare the vehicle price, down payment, loan amount, interest rate, repayment term, fees and total borrowing cost together. If you are considering a plug-in model, verify current federal and provincial incentive eligibility rather than assuming every hybrid qualifies.
The broader Canadian interest-rate environment is also worth monitoring. As of September 2, 2026, the Bank of Canada had maintained its overnight target at 2.25%, but consumer auto-loan rates remain lender- and borrower-specific.
Quick Approvals can provide a starting point for Canadians exploring vehicle financing. Before committing, compare your available options carefully and make sure the final agreement fits your budget for the entire repayment period.
Internal Links for QuickApprovals.ca
- https://quickapprovals.ca/car-loan-calculator-canada/
- https://quickapprovals.ca/online-car-loan-approval-canada/
- https://quickapprovals.ca/low-interest-car-loans-canada/
- https://quickapprovals.ca/car-loan-pre-approval-canada/
- https://quickapprovals.ca/plug-in-hybrid-financing-canada/
- https://quickapprovals.ca/hybrid-car-loan-calculator-canada/
Authority Outbound References
- Financial Consumer Agency of Canada — Financing a Car
- Financial Consumer Agency of Canada — Shopping Around for Auto-Financing
- Government of Canada — Electric Vehicle Affordability Program
- Bank of Canada — Policy Interest Rate
- Bank of Canada — Interest Rates Posted by Major Chartered Banks
- Government of Canada — Buying or Leasing a Vehicle