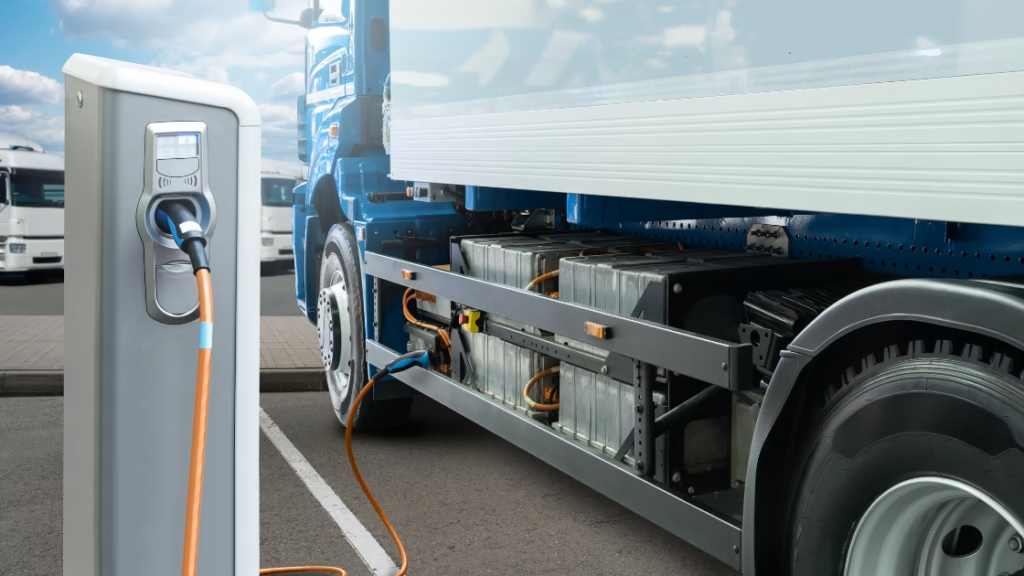
Buying an electric truck can be a major financial decision. The vehicle may offer lower energy and maintenance costs, but the purchase price can still be substantial, particularly when the truck is being used for business, delivery, construction, service work or fleet operations. That makes choosing the right electric truck financing Canada strategy just as important as choosing the right vehicle.
Whether you are an individual buyer considering EV truck auto loans Canada, a contractor replacing a conventional work truck, or a business looking for commercial electric truck loans Canada, financing should be evaluated on the complete cost of ownership rather than the monthly payment alone. Loan term, interest rate, down payment, vehicle value, operating costs and available incentives can all materially change the economics.
Canada’s EV incentive landscape also requires careful attention. Federal programs have changed, and eligibility depends on vehicle type, transaction value, buyer and program rules. For example, the federal Electric Vehicle Affordability Program provides up to $5,000 in 2026 for qualifying light-duty EVs, while the former federal medium- and heavy-duty zero-emission vehicle incentive program closed on March 31, 2026. electric truck financing Canada
This guide explains how to approach electric truck financing Canada responsibly, compare financing sources, estimate payments, understand battery electric truck rates Canada, evaluate green truck financing incentives Canada, and improve your chances of obtaining an approval that makes financial sense.
What Electric Truck Financing Canada Means for Buyers
Electric truck financing Canada refers to financing arrangements used to purchase an eligible electric truck through a bank, credit union, dealership finance department, independent lender or financing broker. The structure can resemble conventional vehicle financing, but lenders may assess additional factors such as vehicle classification, purchase price, expected resale value, business use and the applicant’s ability to support the payment.
For consumers, financing is generally based on income, credit history, existing obligations, down payment and the vehicle being purchased. For businesses, the assessment can become more detailed. A lender may consider business financial statements, time in business, revenue, cash flow, commercial use and the expected role of the vehicle in generating income. electric truck financing Canada
The Financial Consumer Agency of Canada confirms that Canadian vehicle buyers can obtain financing through dealerships or directly through financial institutions. Dealerships may arrange financing through manufacturer finance divisions, banks, credit unions or independent finance companies. electric truck financing Canada
That means there is no single financing route that is automatically best for every electric-truck buyer.
Why EV Truck Auto Loans Canada Require a Different Approach
EV truck auto loans Canada deserve careful analysis because an electric truck can have a different purchase price, operating profile and depreciation pattern from a conventional vehicle. A buyer should therefore avoid comparing loans exclusively by monthly payment.
Suppose a truck costs $70,000 before applicable taxes and fees and is financed at an illustrative 8% annual rate. A five-year loan would produce a payment of approximately $1,419 per month and about $15,161 in interest over the term. Extending the same illustrative loan to seven years reduces the payment to approximately $1,091, but total interest rises to about $21,647. EV truck auto loans Canada
The lower payment may look attractive, but it comes at a higher total borrowing cost. FCAC specifically warns Canadian consumers that longer vehicle-financing terms can increase total interest and contribute to negative-equity problems.
For an electric truck, the correct question is therefore not simply, “What payment can I get?” It is, “What financing structure fits the truck’s useful life, operating savings and my ability to repay it?” EV truck auto loans Canada
Commercial Electric Truck Loans Canada: Personal Versus Business Financing
Commercial electric truck loans Canada are particularly relevant when an electric truck is purchased primarily for business operations. A contractor, delivery company, trades business, landscaping company or service operation may have different financing needs from a consumer buying a truck for personal transportation.
Business borrowers should consider whether the vehicle will generate measurable operating savings. Electricity costs, maintenance requirements, charging infrastructure, insurance, financing costs and utilization should be included in the calculation. commercial electric truck loans Canada
A business should also separate the vehicle’s purchase economics from its financing economics. A truck can be operationally efficient but still be expensive if financed over an unnecessarily long period at an unsuitable rate.
Before applying, prepare a realistic business cash-flow picture. Include monthly revenue, fixed expenses, payroll, existing debt payments, insurance, charging costs, maintenance and the proposed truck payment. A lender needs confidence that the financing remains manageable even during weaker months. commercial electric truck loans Canada
Businesses should also discuss tax treatment and capital-cost considerations with a qualified Canadian tax professional rather than assuming that every electric truck receives identical tax treatment. commercial electric truck loans Canada
Battery Electric Truck Rates Canada: What Determines Your Rate?
Battery electric truck rates Canada are not determined by the truck’s electric powertrain alone. The financing rate is generally influenced by the borrower’s overall risk profile and the transaction being financed.
Important factors can include:
- Credit history and repayment behaviour
- Income or business cash flow
- Existing debt obligations
- Down payment
- Loan amount
- Loan term
- Vehicle age and value
- New versus used vehicle
- Personal versus commercial use
- Business operating history
- Lender policies
- Security and documentation requirements
There is no responsible universal rate that applies to every Canadian electric-truck buyer. Promotional manufacturer financing, bank financing and alternative financing can all produce different offers.
The best way to evaluate battery electric truck rates Canada is to compare the annual interest rate, payment, term, fees and total borrowing cost together.
Illustrative Electric Truck Financing Cost
| Example | Loan Amount | Illustrative Rate | Term | Approx. Monthly Payment | Approx. Interest |
|---|---|---|---|---|---|
| Example A | $70,000 | 8% | 60 months | $1,419 | $15,161 |
| Example B | $70,000 | 8% | 84 months | $1,091 | $21,647 |
| Example C | $100,000 | 7% | 72 months | $1,705 | $22,753 |
| Example D | $100,000 | 7% | 84 months | $1,509 | $26,779 |
These are illustrative calculations, not advertised Canadian lending rates or guaranteed offers. Actual financing depends on the applicant, vehicle, lender and final contract.
Green Truck Financing Incentives Canada: Check Eligibility Before Borrowing
Green truck financing incentives Canada can materially affect the amount a buyer needs to finance, but incentives should never be assumed without checking current eligibility.
The federal government’s current EV incentive information states that the Electric Vehicle Affordability Program can provide up to $5,000 in 2026 for qualifying light-duty EV purchases or leases, subject to program conditions. Most personal vehicles, including light pick-up trucks, fall into the light-duty category.
However, the previous federal Incentives for Medium- and Heavy-Duty Zero-Emission Vehicles program is closed. Transport Canada states that the program ended on March 31, 2026.
This distinction matters. A buyer considering green truck financing incentives Canada should identify the exact vehicle classification before building an affordability calculation around an incentive.
Provincial and territorial programs can also change. The Government of Canada currently identifies Manitoba, Quebec and Yukon among jurisdictions with EV-related incentives, while individual programs have their own eligibility rules. green truck financing incentives Canada
Never treat an incentive as guaranteed until the applicable government or program administrator confirms that the specific vehicle and transaction qualify. green truck financing incentives Canada
How to Get Electric Truck Financing Canada Step by Step
Step 1: Establish the Total Truck Budget
Start with the complete purchase cost rather than the advertised truck price. Consider taxes, registration, dealer fees, accessories, charging equipment and any other costs that may be financed.
Then determine how much cash you can comfortably contribute without draining your emergency reserves.
A larger down payment can reduce the amount financed, monthly payment and interest expense. However, putting every available dollar into the truck can leave a business or household vulnerable to unexpected expenses.
Step 2: Review Your Financial Position
Before submitting an application, review income, existing debt and credit obligations. For businesses, examine revenue consistency and cash flow.
Correct documentation matters. If your application says one income amount while your supporting documents show another, the lender may need additional verification.
Step 3: Choose the Appropriate Financing Channel
Compare banks, credit unions, dealership financing, independent lenders and brokers.
A bank may be attractive for a strong borrower with an established relationship. Dealership financing can be convenient and may provide manufacturer promotions. An independent lender may offer broader underwriting flexibility. A broker can potentially help compare multiple financing sources.
Canada’s financial consumer guidance recommends obtaining quotes from multiple dealers and lenders and comparing the overall financing arrangement rather than focusing only on one number.
Step 4: Get the Truck and Financing Offer Evaluated Together
A financing offer cannot be evaluated properly without knowing the exact vehicle.
Confirm the purchase price, model year, mileage if applicable, vehicle classification, down payment, financed amount, term, interest rate and fees.
Step 5: Compare the Total Cost
Calculate the total amount you will pay over the full term.
For example, a $70,000 loan at an illustrative 8% rate costs approximately $85,161 over 60 months but approximately $91,647 over 84 months. The seven-year structure reduces the payment by roughly $328 per month but adds roughly $6,486 in interest.
That difference illustrates why electric truck financing Canada should be evaluated using total cost rather than payment alone.
Step 6: Read the Final Agreement
Before signing, review the interest rate, payment schedule, term, fees, insurance products, optional products and total cost of borrowing.
FCAC states that lenders or dealers must provide disclosure information before finalizing the agreement, including important information about the total cost of borrowing.
Electric Truck Financing Eligibility and Requirements
Electric truck financing Canada eligibility varies between lenders, but applicants should expect to provide information demonstrating identity, income, residence and repayment capacity.
Typical consumer documentation can include:
- Government-issued identification
- Proof of residence
- Employment information
- Recent income documentation
- Banking information
- Details of existing financial obligations
- Vehicle purchase information
Commercial applicants may additionally need:
- Business registration information
- Business financial statements
- Revenue documentation
- Business bank statements
- Tax information
- Details about existing commercial debt
- Vehicle-use information
- Purchase invoice or dealer documentation
There is no single universal minimum credit score for every electric-truck loan. A stronger credit profile can improve the range of financing options, but lenders can consider the complete application.
For borrowers with weaker credit, affordability and documentation become particularly important. An applicant should not attempt to conceal debts, inflate income or provide inaccurate information simply to obtain approval.
Banks vs Lenders vs Brokers for Electric Truck Financing
| Feature | Banks | Independent Lenders | Financing Brokers |
|---|---|---|---|
| Typical strength | Established borrowers | Flexible borrower profiles | Multiple financing options |
| Convenience | High for existing customers | Varies | High |
| Credit flexibility | Often more structured | Can be broader | Depends on lender network |
| Commercial applications | Available | Available depending on lender | Can match specialized options |
| Rate comparison | Usually one institution | Usually one lender | Potentially multiple lenders |
| Approval process | Can be structured | Varies | Application matching |
| Best approach | Compare offer | Review terms carefully | Compare matched offers |
No category automatically produces the cheapest financing. A borrower should compare actual offers rather than assume that banks always provide the lowest rate or alternative lenders always cost more.
The Financial Consumer Agency of Canada notes that a dealer does not necessarily have to provide the lowest interest rate and encourages borrowers to compare offers.
Practical Canadian Case Study: Personal Electric Truck Buyer
Consider a hypothetical Ontario buyer purchasing a $70,000 electric truck. The buyer has stable employment, strong credit and $10,000 available for a down payment.
Instead of financing the entire purchase, the buyer could finance $60,000. At an illustrative 6% rate over 60 months, the payment would be approximately $1,160 per month.
The buyer should then compare that payment against insurance, charging, maintenance and other vehicle costs. If the truck replaces a gasoline vehicle used heavily for commuting or work, the operating-cost difference may improve the overall household budget.
However, the buyer should not assume that lower energy costs automatically justify a larger loan. Affordability must still be evaluated using the household’s complete financial position.
Practical Canadian Case Study: Small Business Electric Truck
Imagine a Canadian service business considering a $100,000 electric truck. The business expects to use the vehicle extensively and believes reduced energy and maintenance costs could improve operating economics.
The business obtains an illustrative 7% financing structure over 72 months, producing a payment of approximately $1,705 per month.
Instead of evaluating the truck only by that payment, management should create a monthly operating model covering expected mileage, charging, insurance, maintenance, financing, downtime and revenue generated by the truck.
The key question becomes whether the vehicle produces enough operational value to justify its financing obligation. This approach is more useful than simply asking whether the business can technically qualify for the loan.
How to Accelerate Electric Truck Financing Approval
Electric truck financing Canada approval can become more efficient when the application is complete and internally consistent.
Start by selecting a realistic truck budget. An application for a vehicle that is clearly disproportionate to income or business cash flow can create unnecessary underwriting concerns.
Next, prepare documentation before applying. Having identification, income evidence, banking information and vehicle details ready can reduce delays caused by missing information.
If you are self-employed or operating a business, organize financial documents in advance. Consistent records make it easier for a lender to understand the applicant’s financial position.
Avoid submitting numerous unrelated applications simply because one lender has not responded immediately. Instead, understand how each application will be handled and compare financing strategically.
Finally, consider a meaningful down payment when financially appropriate. Reducing the amount financed can strengthen the overall transaction and lower the amount of interest paid.
Critical Mistakes to Avoid With Electric Truck Financing
Choosing the Lowest Monthly Payment
The lowest payment often comes from a longer term. That does not necessarily make it the cheapest loan.
Assuming an EV Incentive Applies
Program eligibility can depend on vehicle classification, price, buyer status and other conditions. The former medium- and heavy-duty federal incentive program, for example, is now closed.
Ignoring Total Cost of Ownership
Charging savings are valuable, but insurance, financing, depreciation, tires, maintenance and infrastructure also matter.
Financing Too Much
A large loan can become difficult to manage if income falls or business utilization declines.
Focusing Only on the Advertised Rate
A rate should be evaluated alongside fees, term, payment and total borrowing cost.
Extending the Term Without Calculating Interest
FCAC’s guidance demonstrates that long vehicle-financing terms can increase total interest and negative-equity risk.
Signing Without Reading the Disclosure
Canadian borrowers should understand the financing agreement before signing. FCAC recommends reviewing the disclosure statement and obtaining a copy.
Frequently Asked Questions About Electric Truck Financing Canada
Can I get electric truck financing Canada for a business?
Yes, business applicants can seek financing for electric trucks, although eligibility and underwriting requirements vary by lender. Commercial borrowers should be prepared to demonstrate business activity, revenue or cash flow, repayment capacity and the intended use of the vehicle. The strongest application is one where the requested financing is reasonable relative to business finances and the truck’s expected contribution to operations.
Are battery electric truck rates Canada lower than conventional truck financing?
Not automatically. Battery electric truck rates Canada depend on the borrower, vehicle, lender, term and transaction. Some manufacturers or lenders may offer promotional financing for particular vehicles, but there is no universal electric-truck rate. Compare actual offers using the interest rate, total interest, fees and repayment term rather than assuming the powertrain determines the rate.
Can I use green truck financing incentives Canada to reduce my loan?
Potentially, but the incentive must first apply to the specific vehicle and buyer. The current federal EV incentive structure includes eligibility requirements for qualifying light-duty vehicles, while the previous federal medium- and heavy-duty zero-emission vehicle incentive program has closed. Provincial programs may also have separate requirements. Verify the current program before including an incentive in your financing budget.
Are EV truck auto loans Canada available with imperfect credit?
Potentially. Financing decisions can consider more than a credit score, including income, existing obligations, down payment and vehicle details. Applicants with weaker credit may face fewer options or higher borrowing costs. Improving affordability, providing complete documentation and selecting a reasonably priced vehicle can strengthen an application.
Should I finance an electric truck over 84 months?
An 84-month structure can reduce the monthly payment, but it generally increases total interest and can extend the period during which the loan balance exceeds the vehicle’s value. FCAC specifically highlights the risks associated with long vehicle loans. Choose the shortest term that comfortably fits your budget rather than automatically selecting the longest available term.
Is commercial electric truck loans Canada financing different from a personal truck loan?
It can be. Commercial financing may require additional business information and can involve different underwriting considerations. The lender may want to understand business revenue, cash flow, operating history and how the truck will be used. Businesses should also consider tax and accounting implications with qualified professionals.
Should I choose a bank, lender or broker?
The best option depends on your financial profile and the specific truck. A bank may be competitive for a strong existing customer, while an independent lender may provide different underwriting options. A broker may help connect borrowers with multiple financing sources. The most important step is to compare the actual offers and understand the complete cost.
What should I check before signing an electric truck loan?
Check the interest rate, financed amount, payment, term, total borrowing cost, fees, optional insurance or protection products, payment schedule and any other contractual conditions. Ask for the disclosure documents and read them carefully. FCAC recommends shopping around and understanding the financing agreement before signing.
Final Thoughts: Choosing Smarter Electric Truck Financing Canada
The right electric truck financing Canada strategy is not simply the loan that produces the smallest monthly payment. It is the financing structure that balances the truck’s purchase price, interest cost, term, operating economics, business or household cash flow and long-term vehicle value.
For personal buyers, the priority should be affordability and manageable repayment. For businesses, the analysis should go further by examining utilization, revenue contribution, charging costs, maintenance, cash flow and the expected economic life of the vehicle.
Buyers considering EV truck auto loans Canada should compare multiple financing options, while businesses researching commercial electric truck loans Canada should prepare stronger financial documentation before applying. Anyone evaluating battery electric truck rates Canada should compare complete loan costs rather than relying on advertised rates alone.
Government programs can also change quickly. Current green truck financing incentives Canada should therefore be verified through official federal and provincial sources before being included in a purchase calculation.
If the numbers work, the right financing can turn an electric truck from a major capital purchase into a manageable long-term transportation or business asset. Start with a realistic budget, compare financing offers, verify incentive eligibility and choose a repayment structure that remains comfortable even when circumstances change.
Internal Links for QuickApprovals.ca
- https://quickapprovals.ca/ — Core auto loan financing page
- https://quickapprovals.ca/used-car-financing-canada/ — Supporting vehicle financing resource
- https://quickapprovals.ca/bad-credit-car-loans-canada/ — Financing options for borrowers with credit challenges
- https://quickapprovals.ca/car-loans-for-uber-drivers-canada/ — Vehicle financing for commercial/gig use
- https://quickapprovals.ca/contract-employee-car-loans/ — Financing guidance for independent contractors
- https://quickapprovals.ca/car-loan-for-fire-trucks-canada/ — Specialized truck financing resource
Authority Outbound References
- Government of Canada — Electric Vehicle Incentives
- Financial Consumer Agency of Canada — Financing a Car
- Financial Consumer Agency of Canada — Shopping Around for Auto-Financing
- Financial Consumer Agency of Canada — Financial Risks When Buying a Car
- Transport Canada — Zero-Emission Trucking Program
- Government of Canada — Greening Commercial Vehicles and Fleets