Buying a vehicle in Canada in September 2026 can feel like a race against rising prices, changing financing offers and complicated dealership negotiations. The rate you accept today can affect your monthly payment and the total amount you pay for years. That is why finding the best car loan rates September 2026 Canada is not simply about finding the lowest percentage advertised online. It is about comparing financing offers based on the same vehicle price, loan amount, repayment term and borrower profile.
The Canadian lending environment also deserves attention. The Bank of Canada maintained its overnight policy rate at 2.25% on September 2, 2026, while noting that inflation risks remain elevated and economic conditions continue to face uncertainty. Meanwhile, the latest Bank of Canada lending data available for this comparison shows an average rate of 6.55% on newly advanced auto loans from chartered banks in June 2026. That is a market indicator—not a guaranteed rate for any individual borrower.
For a Canadian buyer, this means the smartest approach to current auto loan interest rates Canada is to use market data as a reference point, then obtain personalized financing offers and compare their complete borrowing costs. This guide explains what September 2026 buyers should know, how lenders determine rates, how banks compare with other financing sources, how to reduce borrowing costs and how to prepare for a faster approval. best car loan rates September 2026 Canada
Understanding the Best Car Loan Rates September 2026 Canada
The best car loan rates September 2026 Canada should be understood as competitive financing that fits your particular financial situation, not as one universal number available to everyone. Canadian lenders consider several variables when pricing an auto loan, including credit history, income, existing obligations, vehicle type and age, amount financed, loan term, down payment and the lender’s own underwriting criteria. This is why two Canadians purchasing the same vehicle can receive different financing offers.
A promotional rate may also be restricted to specific vehicles, terms, credit profiles or manufacturer programs. Major lenders such as RBC, TD and Scotiabank currently advertise competitive vehicle financing and special-rate programs, but their public pages also make clear that actual rates depend on circumstances and available offers.
The most important distinction is between an advertised rate and an approved rate. An advertisement can attract attention with a low percentage, but that percentage may apply only to selected vehicles or highly qualified applicants.
A personalized financing offer tells you what a particular lender is prepared to provide based on your application. Therefore, when searching for lowest APR car financing Canada, compare actual offers rather than assuming that the lowest advertised number is automatically available to you. best car loan rates September 2026 Canada
Current Auto Loan Interest Rates Canada in September 2026
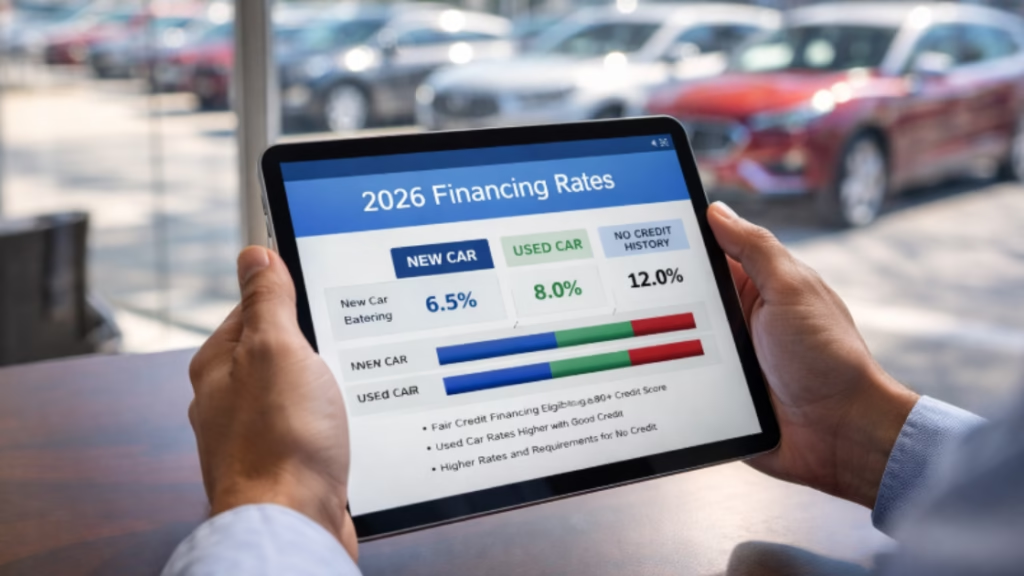
The latest current auto loan interest rates Canada should be evaluated using both market data and individual lender offers. The Bank of Canada reported an average rate of 6.55% for newly advanced auto loans from chartered banks in June 2026. This figure is useful as a national benchmark, but it does not represent a minimum, maximum or guaranteed consumer rate.
By September, the Bank of Canada’s policy rate remains at 2.25%. The central-bank rate influences the broader borrowing environment, but it is not the rate consumers automatically receive on vehicle financing. Auto lenders consider funding costs, credit risk, operating costs, vehicle characteristics and borrower-specific information when setting loan pricing.
This distinction matters when searching for updated car loan rates today Canada. A consumer should not assume that a 2.25% Bank of Canada policy rate means a 2.25% car loan is available. Likewise, a national auto-loan average should not be interpreted as a quote for your application. current auto loan interest rates Canada
For September 2026, the practical benchmark is therefore simple: identify the current market environment, obtain personalized offers and compare those offers on an identical basis. current auto loan interest rates Canada
How to Compare September Rates Canada Without Making a Costly Mistake
A proper compare September rates Canada strategy starts by standardizing the comparison. If one lender quotes $30,000 over 60 months and another quotes $30,000 over 84 months, comparing only the monthly payments can create a misleading result. The longer term may produce a smaller payment while increasing the total interest paid.
Use the following comparison framework: compare September rates Canada
| Factor | What to Compare |
|---|---|
| Interest rate | Annual rate offered by each lender |
| APR/disclosure | Applicable borrowing-cost disclosure |
| Amount financed | Same amount for each offer |
| Loan term | Compare identical repayment periods |
| Payment frequency | Monthly, biweekly or weekly |
| Fees | Administration and other applicable charges |
| Optional products | Warranties, insurance and protection products |
| Total repayment | Amount paid over the full term |
| Early repayment | Whether and how extra payments are permitted |
The Financial Consumer Agency of Canada recommends shopping around and comparing financing offers rather than assuming a dealership has provided the lowest available rate. A dealer does not have to offer the lowest interest rate, and consumers can ask about financing from multiple lenders where available. compare September rates Canada
What Determines Your Car Loan Rate in Canada?
Your car loan rate Canada September 2026 is influenced by more than your credit score. Lenders assess the complete application because the loan represents a financial risk over several years. A strong credit history can help, but income, debt obligations, vehicle characteristics, loan structure and other information can also affect the final offer.
Credit History and Borrowing Record
Your credit history helps lenders understand how you have handled previous credit. TransUnion Canada explains that lenders report account activity to Canadian credit bureaus and that information can vary between credit reports because lenders do not necessarily report to both bureaus or at identical times.
Before applying, review your credit information and check for inaccuracies. This can be especially important if you are preparing for a major purchase and expect lenders to evaluate your credit file.
Income and Existing Debt
Lenders also need information demonstrating that you can manage the proposed payment. Proof of income can include a paystub or other acceptable documentation. TD, for example, identifies proof of income, government-issued identification and payment information among documents applicants may need for vehicle financing.
Vehicle Age and Type
The vehicle itself can influence financing. Some lenders impose age restrictions or different terms depending on whether the vehicle is new or used. Scotiabank, for example, advertises financing for new vehicles and vehicles up to seven years old under its auto-loan program.
Loan Term
The repayment period is one of the most important variables in the total cost. A longer term generally reduces the required payment but gives interest more time to accumulate.
That means a borrower searching for lowest APR car financing Canada should not evaluate the rate separately from the repayment term.
Interest Rates and Cost Breakdown: What a Small Rate Difference Can Mean
Consider an illustrative $30,000 auto loan with a five-year repayment period and no additional financed fees: updated car loan rates today Canada
| Illustrative Rate | Approx. Monthly Payment | Approx. Total Payments | Approx. Interest |
|---|---|---|---|
| 5% | $566 | $33,967 | $3,967 |
| 6% | $580 | $34,800 | $4,800 |
| 7% | $594 | $35,644 | $5,644 |
| 8% | $608 | $36,492 | $6,492 |
These figures are mathematical illustrations rather than lender quotations. They demonstrate the importance of comparing updated car loan rates today Canada instead of focusing only on the payment displayed by a salesperson.
A three-percentage-point difference between 5% and 8% on this hypothetical loan produces more than $2,500 in additional interest. The effect can become considerably larger when the amount borrowed or repayment term increases. updated car loan rates today Canada
The term can be just as important. A longer loan can make a vehicle appear more affordable because the required payment is spread over more months, but the borrower may pay substantially more interest overall.
The Financial Consumer Agency of Canada specifically advises consumers to consider the total cost of borrowing and not simply the monthly payment. updated car loan rates today Canada
Banks vs Lenders vs Brokers for September 2026 Car Financing
There is no single financing source that provides the same terms to every Canadian borrower. A useful compare September rates Canada exercise should consider the differences between banks, dealership lenders and other financing channels.
| Financing Source | Typical Advantage | Important Consideration |
|---|---|---|
| Bank | Established banking relationship and conventional financing | Rate depends on application and vehicle |
| Credit union | Member-based lending structure | Membership and regional rules may apply |
| Dealership finance | Convenient and multiple lender relationships may be available | Dealer does not necessarily provide the lowest rate |
| Specialized lender | May consider broader borrower profiles | Pricing can reflect greater lending risk |
| Financing broker/platform | Can help connect borrowers with financing sources | Confirm lender, rate and final terms |
RBC offers dealership financing through participating dealers and states that special financing rates may be available through partner manufacturers. Its financing calculator also notes that rates can vary based on incentive programs, credit history and the structure of the application.
TD offers vehicle financing through a nationwide dealership network and provides financing options for new and used vehicles, including terms of up to 96 months on select vehicles.
Scotiabank similarly offers auto financing through thousands of dealerships and advertises financing for vehicles meeting its program requirements.
The lesson is straightforward: compare the actual financing agreement, not merely the name of the lender.
Step-by-Step Guide to Finding Competitive September 2026 Rates
Step 1: Set Your Vehicle Budget First
Before looking for best car loan rates September 2026 Canada, establish the maximum vehicle cost that fits comfortably into your overall budget. Include the financing payment as well as insurance, fuel, maintenance, registration and other ownership costs.
An approval tells you how much a lender may be willing to finance. It does not establish what you personally should spend.
Step 2: Check Your Credit Information
Review your credit reports before submitting applications. Look for incorrect personal information, accounts that do not belong to you, reporting errors or outdated information.
TransUnion notes that Canadian lenders may report to one or both major credit bureaus, so differences between reports can occur.
Step 3: Gather Documentation
Prepare government-issued identification, income documentation, employment details, residence information and vehicle information. Having these documents ready can make the application process smoother.
Step 4: Obtain Comparable Financing Offers
Request offers based on the same amount borrowed and the same repayment period whenever possible. This creates an apples-to-apples comparison.
Step 5: Compare the Total Cost
Look beyond the payment. Record the interest rate, applicable APR or borrowing-cost disclosure, fees, optional products and total repayment amount.
Step 6: Negotiate
If another lender provides a more competitive offer, ask whether the dealership or current lender can match or improve the financing terms.
Step 7: Read the Contract Before Signing
Federal, provincial and territorial consumer-protection rules can apply depending on the lender and transaction. FCAC states that lenders or dealers must provide required disclosure information before finalizing the agreement, including information about the total cost of borrowing.
Eligibility and Requirements for Canadian Auto Financing
Eligibility for current auto loan interest rates Canada varies between lenders, so there is no universal minimum income or credit score that guarantees a particular offer. A typical application may require identification, proof of income, employment information, residential information and details about the vehicle being financed.
A lender may also assess your credit history, existing debts, down payment and the proposed loan structure. Vehicle age and type can affect eligibility because lenders may place restrictions on the collateral they are willing to finance.
Newcomers can also have dedicated financing programs. Scotiabank’s StartRight Auto Finance program, for example, states that eligible newcomers may qualify without a Canadian credit history, subject to its program requirements.
This reinforces an important point: being declined by one lender does not necessarily mean that every lender will reach the same decision. Financing policies differ, and borrowers should compare legitimate options rather than making assumptions based on one application.
Canadian Case Study: Strong Credit Borrower
Consider a Canadian buyer financing $30,000 for 60 months. The borrower has stable income, a strong credit history and manageable existing obligations. lowest APR car financing Canada
The first dealership offers a financing package at 7%. Another lender provides 6.5% for the same amount and term. A manufacturer promotion offers a lower promotional rate, but only on selected vehicles and under specific eligibility conditions.
The borrower should compare all three offers using the same amount financed and repayment period. If the promotional financing requires giving up a substantial cash incentive, the borrower should calculate both scenarios instead of automatically selecting the lower advertised rate.
This is how lowest APR car financing Canada should be approached: compare the complete financial outcome, not one number in isolation.
Canadian Case Study: Longer-Term Financing
Now consider a borrower who wants a $40,000 vehicle and is focused primarily on keeping the monthly payment low.
A longer repayment period can reduce the required payment, making the vehicle appear more affordable. However, extending the loan can substantially increase the amount of interest paid.
The borrower may therefore have two different goals: minimize the monthly payment or minimize the total borrowing cost. Those objectives are not always identical.
Before accepting a longer term, calculate the total amount repaid and consider whether the vehicle remains affordable after insurance, maintenance, fuel and other ownership expenses.
Canadian Case Study: Used Vehicle Buyer
A used-car buyer may receive different financing terms from a new-car buyer because vehicle age and lender policies can affect eligibility and pricing. RBC, for example, states that its dealer financing can be available for vehicles up to 10 years old, while other lenders can apply different vehicle-age requirements.
A used-vehicle buyer should therefore compare the vehicle’s purchase price, financing rate, term and expected ownership costs together. A lower vehicle price does not automatically mean lower total financing costs if the rate is significantly higher.
How to Accelerate Auto Loan Approval
Preparing carefully can make the financing process more efficient. Start by ensuring that your identification and income documents are current. Verify your employment information and make sure the information on your application is accurate and consistent.
Know the approximate amount you want to finance before approaching lenders. If you have a trade-in, determine its estimated value and whether there is an existing loan balance. Negative equity can affect the amount that ultimately needs to be financed.
You should also decide how much you can reasonably provide as a down payment. A larger down payment reduces the amount borrowed and can lower the total interest cost, although you should avoid draining emergency savings simply to increase the down payment.
Finally, understand the lender’s process. TD, for example, identifies several documents applicants may need, while RBC provides pre-qualification and affordability tools for prospective vehicle buyers.
Critical Mistakes to Avoid When Comparing September Rates
Focusing Only on the Monthly Payment
A lower payment can result from a longer term rather than a cheaper loan. Always calculate the total repayment.
Assuming the Advertised Rate Is Guaranteed
Promotional rates can have vehicle, term, credit or program restrictions. Confirm that the rate applies to your exact situation.
Ignoring Optional Products
Extended warranties, insurance products and other optional products can increase the amount financed and therefore the total borrowing cost.
Comparing Different Loan Terms
A 60-month offer and an 84-month offer should not be compared solely by monthly payment.
Signing Before Reviewing Disclosure
FCAC advises consumers to read the disclosure statement carefully because it explains the total cost of borrowing and other important information.
Assuming a Dealer Automatically Provides the Lowest Rate
The FCAC explicitly states that a dealer does not have to offer the lowest interest rate and recommends shopping around.
Signing Multiple Purchase Agreements
FCAC warns that consumers should not sign a contract with more than one dealership at the same time because they may not be able to get out of the agreements.
FAQs About Best Car Loan Rates September 2026 Canada
What are the best car loan rates September 2026 Canada?
The best car loan rates September 2026 Canada depend on the borrower, vehicle, lender and financing structure. The Bank of Canada reported an average rate of 6.55% for newly advanced auto loans from chartered banks in June 2026, but that figure is a national market statistic rather than a guaranteed consumer offer. Your actual rate can be higher or lower. The most reliable approach is to obtain personalized offers and compare them using the same amount and term.
What are the current auto loan interest rates Canada?
The latest available Bank of Canada data used in this comparison reported an average 6.55% rate on newly advanced auto loans from chartered banks in June 2026. By September 2026, the Bank of Canada’s policy rate is 2.25%, but the policy rate should not be confused with an individual auto-loan rate. Lenders independently price auto financing based on credit risk, vehicle characteristics, funding costs and other factors.
How can I find the lowest APR car financing Canada?
To search for lowest APR car financing Canada, compare multiple actual offers rather than relying on advertisements. Use the same loan amount, vehicle price and repayment term when comparing lenders. Review the interest rate, applicable APR or borrowing-cost disclosure, fees, optional products and total amount repaid. A slightly higher monthly payment can sometimes result in substantially lower total borrowing costs if the repayment period is shorter.
Should I use a bank or dealership for car financing?
Both can provide legitimate financing options. Canadian dealerships may arrange financing through banks, manufacturer finance divisions, credit unions or independent finance companies. The important issue is not simply where you apply, but whether the financing offer is competitive for your particular circumstances. Obtain comparable offers and negotiate when possible.
Does a lower Bank of Canada rate automatically mean lower car loan rates?
No. The Bank of Canada policy rate influences broader financial conditions, but consumers do not borrow for vehicles directly at the central-bank policy rate. The Bank maintained its policy rate at 2.25% on September 2, 2026, while auto lenders continue to determine consumer financing based on their own pricing and underwriting models.
Is a longer car loan better because the monthly payment is lower?
Not necessarily. A longer term can reduce the required payment because the principal is spread over more months, but it can increase the total interest paid. The correct comparison is the total amount repaid, not simply the monthly payment. If you are evaluating updated car loan rates today Canada, compare identical loan terms whenever possible.
Can I negotiate my car loan interest rate?
You can ask lenders or dealerships whether they can improve the financing offer. FCAC recommends shopping around and negotiating rather than assuming the dealer has provided the lowest available rate. A competing financing offer can give you useful information when discussing the final terms, although the lender is not obligated to match another offer.
What documents are needed for a car loan in Canada?
Requirements vary by lender, but applicants may need government-issued identification, proof of income, employment information, residential information and banking or payment details. TD, for example, identifies a paystub, government-issued photo ID and void cheque or pre-authorized payment form among documents applicants may need for vehicle financing. Having accurate documentation ready can help prevent unnecessary delays during the application process.
Final Thoughts on the Best Car Loan Rates September 2026 Canada
Finding the best car loan rates September 2026 Canada is ultimately about making a complete financing comparison rather than chasing a single advertised percentage. Canada’s policy rate is currently 2.25%, while the latest available Bank of Canada auto-loan data used here shows an average 6.55% rate for newly advanced auto loans from chartered banks in June 2026. These figures provide useful context, but neither determines the rate you personally receive.
Before signing, compare the actual rate, loan term, amount financed, payment frequency, applicable fees, optional products and total repayment. Check your credit information, prepare your documentation and obtain more than one financing offer when practical. Most importantly, choose a vehicle and payment that fit your overall budget rather than simply maximizing the amount a lender is willing to approve.
For Canadians comparing financing in September 2026, the goal should be informed borrowing: understand the offer, verify the numbers, ask questions and read the agreement before signing.
Internal Links for Quick Approvals
- https://quickapprovals.ca/car-loan-rates-comparison-canada/
- https://quickapprovals.ca/car-loan-interest-rates-2026-canada/
- https://quickapprovals.ca/digital-car-loan-platforms-canada/
- https://quickapprovals.ca/car-loan-soft-credit-check-canada/
- https://quickapprovals.ca/personalized-car-loan-offers-canada/
- https://quickapprovals.ca/best-provincial-car-loan-rates-canada/
Authority Outbound References
- https://www.bankofcanada.ca/core-functions/monetary-policy/key-interest-rate/
- https://www.bankofcanada.ca/2026/09/fad-press-release-2026-09-02/
- https://www.canada.ca/en/financial-consumer-agency/services/loans/financing-car/shop-around.html
- https://www.canada.ca/en/financial-consumer-agency/services/loans/financing-car/how-are-you-protected.html
- https://www.transunion.ca/credit-report
- https://www.rbcroyalbank.com/car-loans/