Introduction: Can You Get a Car Loan While Working Part-Time in Canada?
Getting a car loan can feel challenging when you do not work a traditional full-time job. You might work evenings at a retail store, pick up weekend shifts, work in hospitality, or earn money through more than one job. Although your income may be lower or less predictable than that of a full-time employee, it does not automatically mean you cannot finance a vehicle. An auto loan for part time workers Canada applicants seek is generally assessed according to the lender’s eligibility criteria, verified income, credit history, existing debts, and ability to make regular payments.
The important question is not simply how many hours you work. It is whether your overall financial situation supports the proposed loan. Lenders may consider your average earnings, how long you have been employed, whether your income is consistent, and how much of your monthly income is already committed to rent, bills, credit cards, and other obligations.
A part-time employee with stable earnings and manageable expenses may present a stronger application than someone working full-time but carrying substantial debt. auto loan for part time workers Canada
This guide explains how auto loan for part time workers Canada applications are assessed, what documents you may need, how multiple income sources can help, and how to compare financing options without taking on an unaffordable payment. You will also learn how to prepare your application, estimate borrowing costs, and avoid common mistakes before choosing your next vehicle.
Can Part-Time Employees Qualify for Auto Financing in Canada?
Yes, part-time employees can qualify for vehicle financing in Canada, provided they meet the individual lender’s requirements. There is no single nationwide rule that guarantees approval based on employment status alone. Each lender evaluates applications using its own underwriting policies, and the decision may depend on several factors beyond your job title or weekly working hours. auto loan for part time workers Canada
When assessing an auto loan for part time workers Canada application, a lender may consider: part time income vehicle loans Canada
- Income stability: Whether your earnings have remained reasonably consistent over time.
- Employment history: How long you have worked for your current employer and whether your employment is ongoing.
- Credit history: Your record of making payments on existing credit accounts.
- Debt obligations: How much you already owe and whether your current income can support another payment.
- Down payment: Whether you can contribute money toward the vehicle’s purchase price.
- Vehicle details: The purchase price, age, mileage, and other factors specified by the lender.
- Loan structure: The amount borrowed, interest rate, repayment term, and required payment frequency.
Not every lender weighs these factors equally. Some may require a minimum income or a particular employment history, while others may assess applicants with variable earnings individually.
If you want to qualify with part time job Canada lenders will evaluate, prepare to demonstrate that your income is genuine, reasonably predictable, and sufficient for your obligations. Do not assume that a full-time position is mandatory, but do not assume that every lender will accept every type of part-time income either. auto loan for part time workers Canada
How Lenders Evaluate Part-Time Income for Vehicle Loans
1. Consistent Paycheques and Employment History
A regular paycheque can help establish that you have the capacity to repay a loan. For example, an employee who consistently receives income from a grocery store, pharmacy, restaurant, or retail business may be able to document earnings through pay stubs and bank deposits.
For an auto loan for part time workers Canada applicant, consistency can matter more than having the same monthly income as a full-time worker. If your shifts change from week to week, a lender may review several recent pay periods or other documents to understand your average earnings. The exact period and evidence required depend on the lender.
If you recently started a job, you may have less employment history to demonstrate. That does not automatically disqualify you, but the lender may request additional evidence or assess your application differently. If possible, gather your available pay stubs, employment confirmation, and bank statements before applying. part time income vehicle loans Canada
2. Seasonal, Temporary, and Variable Work
Some Canadians earn more during busy seasons and less during quieter periods. Hospitality, tourism, agriculture, event services, and retail can involve changing schedules or temporary contracts. Other employees receive different hours each week depending on customer demand or staffing needs.
For part time income vehicle loans Canada applicants, the key is to explain the income pattern accurately. A lender may want to distinguish dependable recurring earnings from occasional overtime, seasonal work, or one-time payments. If your earnings fluctuate, use a realistic average supported by documentation rather than your highest-earning month.
Consider whether you could continue making the payment during a slow period. If your income falls significantly during certain months, build a financial buffer before committing to a loan. An approval is useful only when the resulting repayment obligation remains manageable. auto loan for part time workers Canada
3. Credit History and Existing Debt
Your credit profile may influence both approval and the interest rate offered. Lenders can review repayment history, outstanding balances, credit utilization, and other information allowed under applicable rules and their lending policies. auto loan for part time workers Canada
An applicant with part-time earnings and a history of paying bills on time may be in a better position than an applicant with missed payments and substantial outstanding debt. However, credit history is only one part of the assessment. There is no universal credit score that guarantees approval from every Canadian auto lender.
Before applying for an auto loan for part time workers Canada, review your credit report for errors and check whether your current debt payments leave enough room in your budget. If you have limited credit history, ask potential lenders whether they consider applicants with thin credit files and what additional documentation they accept.
Can Multiple Income Sources Improve Your Auto Loan Application?
Yes, additional income sources may strengthen an application when they are legitimate, sufficiently stable, and acceptable under the lender’s policies. Many part-time workers combine earnings from more than one job to cover household expenses. You might work weekday shifts at one employer and weekend shifts at another, for example. multiple income sources car loans Canada
With multiple income sources car loans Canada applicants may be able to demonstrate greater overall repayment capacity, provided the income can be verified and is expected to continue. A lender may ask for separate pay stubs, employment letters, bank statements, or other supporting records for each source.
Potential income sources include:
- Wages from a primary part-time job.
- Earnings from a second part-time position.
- Regular, documented self-employment income, where accepted.
- Other recurring income that the lender permits applicants to declare.
Not every payment will necessarily qualify as eligible income. Occasional cash work, irregular gifts, or unverified deposits may not be accepted in the same way as documented employment earnings. Never inflate your income or present temporary earnings as guaranteed future income. multiple income sources car loans Canada
For example, suppose you receive $1,650 per month from one job and $750 from a second job. If both amounts are consistent and accepted by the lender, your documented monthly income could total $2,400 before any applicable deductions. The lender would still need to evaluate your expenses, debt, credit profile, and proposed vehicle payment.
If you rely on multiple jobs, make sure the schedule is sustainable. A loan should not require you to work an unrealistic number of hours every month simply to stay current on payments. multiple income sources car loans Canada
Eligibility Requirements for Part-Time Car Loan Applicants
Income and Affordability Requirements
There is no single minimum income that applies to every auto loan in Canada. Lenders set their own criteria, and the amount you may qualify to borrow depends on your complete financial circumstances. auto loan for part time workers Canada
Before applying for flexible work auto financing Canada options, calculate your reliable take-home income and compare it with your essential monthly expenses. Include housing, groceries, utilities, phone bills, insurance, existing loan payments, and savings for emergencies. Then estimate the complete cost of owning a vehicle, not just the loan payment.
A lender may assess debt obligations in relation to income, but its specific calculations and thresholds can vary. Your own budget should be more conservative than the maximum payment a lender is willing to approve. flexible work auto financing Canada
Employment and Income Documents
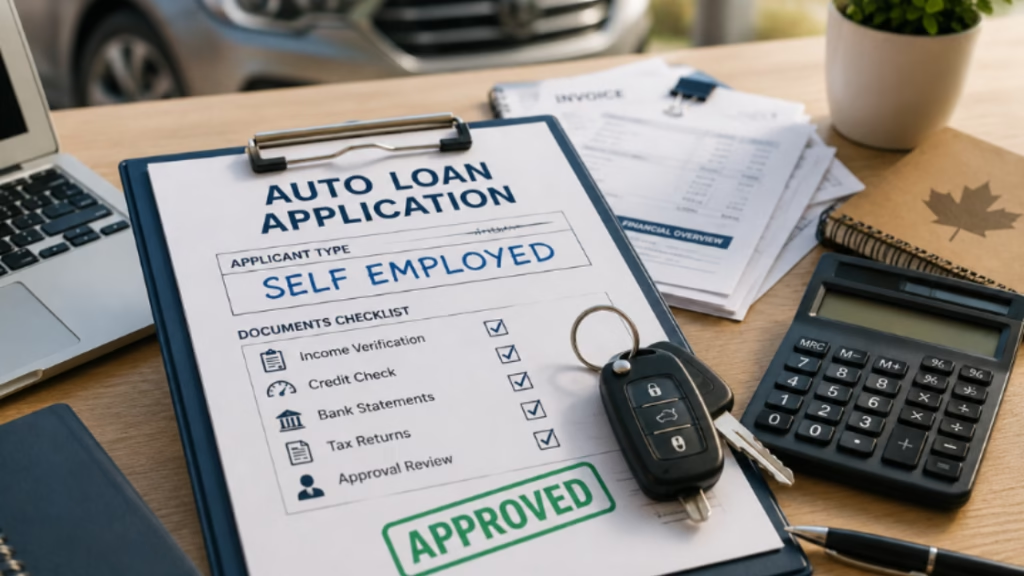
Prepare the documents that best demonstrate your financial situation. Depending on your employment type and the lender’s requirements, these may include: flexible work auto financing Canada
- Recent pay stubs from each employer.
- An employment letter confirming your position and employment status.
- Bank statements showing regular income deposits.
- Government-issued identification accepted by the lender.
- Proof of current residential address.
- Details of existing debts and monthly obligations.
- Information about the vehicle you intend to purchase.
- Down-payment evidence, if applicable.
- Additional tax or self-employment documents, if requested.
Ask the lender which documents are required before submitting an application. Requirements may differ for salaried part-time workers, temporary employees, contract workers, and self-employed applicants. flexible work auto financing Canada
Residency, Age, and Identification
You must meet the lender’s identification and legal eligibility requirements. These may include being the age of majority in the relevant province or territory, providing acceptable identification, and satisfying applicable residency or status requirements. auto loan for part time workers Canada
Do not assume that every lender uses identical rules. If you are new to Canada, have recently changed employment, or have limited Canadian credit history, ask the lender what evidence it accepts before committing to a vehicle purchase. flexible work auto financing Canada
Step-by-Step Guide to Getting Approved
Step 1: Calculate Your Reliable Monthly Income
Start by adding up income you can reasonably expect to continue receiving. For employees with variable hours, review several recent pay periods and calculate a representative average. Separate gross income from take-home income so that you do not accidentally budget money that never reaches your bank account. qualify with part time job Canada
If you work multiple jobs, record each source separately and retain supporting documents. For multiple income sources car loans Canada applications, accurate records help explain where the money comes from and whether it is recurring. part time income vehicle loans Canada
Do not rely on a particularly busy week or an unusually high month. Use conservative estimates that allow for reduced shifts, unpaid time off, or seasonal changes. qualify with part time job Canada
Step 2: Set a Realistic Vehicle Budget
Decide how much you can comfortably spend before shopping for a car. Add the proposed loan payment to insurance, fuel or charging, maintenance, repairs, registration, parking, and other relevant expenses. Used vehicles may also require more immediate maintenance, depending on their condition.
For an auto loan for part time workers Canada application, affordability should be evaluated using your normal income rather than an optimistic scenario. Leave room for emergencies and changes in work hours. If the total vehicle cost would prevent you from covering essential bills, choose a less expensive vehicle or delay the purchase.
Step 3: Review Your Credit Report
Check your credit report through Canada’s credit reporting agencies and look for inaccurate personal information, unfamiliar accounts, incorrect balances, or payment records that appear wrong. Follow the agency’s dispute process if you identify an error. qualify with part time job Canada
Paying existing bills on time and reducing high credit card balances may help improve your financial profile over time, although results are not guaranteed. Avoid taking on unnecessary new debt immediately before applying for vehicle financing.
Step 4: Organize Proof of Income
Gather current pay stubs, employment confirmation, and other evidence that reflects your actual earnings. If you have two employers, make sure the documentation covers both jobs. If your hours fluctuate, be ready to explain the pattern honestly. auto loan for part time workers Canada
When seeking to qualify with part time job Canada lenders, complete and consistent documentation can reduce avoidable delays. Ensure that the information in your application matches your supporting documents, including employment dates and income amounts.
Step 5: Compare Financing Options
Explore financing through banks, credit unions, dealerships, and independent lenders or brokers. Ask whether each option considers part-time employment and how it evaluates variable income.
Compare the annual interest rate, total amount financed, repayment term, fees, payment schedule, and total amount payable. Do not choose an offer simply because it advertises a low monthly payment. A longer term can reduce each payment while increasing the overall borrowing cost. part time income vehicle loans Canada
Step 6: Submit an Accurate Application
Provide complete and truthful information. If the application asks for employment type, describe it accurately. Include additional income only when the form permits it and you can support the amount with appropriate evidence.
Before authorizing a credit check, ask whether the inquiry is a hard or soft inquiry and how the application will be handled. Multiple applications can have different effects depending on the scoring model and circumstances, so avoid indiscriminately submitting forms to numerous providers.
Step 7: Review the Contract Before Signing
Read the final agreement carefully. Confirm the financed amount, interest rate, payment amount, term, applicable fees, and any optional products. Make sure the agreement matches what you were told.
Do not sign a contract you do not understand. Ask for written clarification about optional insurance, warranties, early repayment provisions, late-payment consequences, and any other charges. Only proceed when the payment fits your budget even if your work hours temporarily decline.
Interest Rates and Total Auto Loan Costs
The interest rate offered to a part-time employee is not determined by employment status alone. It can depend on credit history, verified income, debt obligations, vehicle details, lender policies, and the terms of the transaction. No particular rate or approval outcome should be assumed before a lender evaluates the application.
For auto loan for part time workers Canada applicants, comparing the total borrowing cost is especially important because a low payment can conceal a longer repayment period.
Illustrative Auto Loan Payment Comparison
The following examples use a hypothetical $15,000 loan with fixed annual interest, monthly payments, and no additional fees. Figures are rounded and are provided for illustration, not as current lender quotes. part time income vehicle loans Canada
| Hypothetical annual interest rate | Loan term | Approx. monthly payment | Approx. total interest |
|---|---|---|---|
| 7% | 36 months | $463 | $1,670 |
| 7% | 60 months | $297 | $2,820 |
| 12% | 36 months | $498 | $2,930 |
| 12% | 60 months | $334 | $5,040 |
The table illustrates two important points. First, a higher interest rate can materially increase the cost of borrowing. Second, extending the repayment term can reduce the monthly payment but increase total interest.
Actual contracts may differ because of fees, payment timing, taxes, down payments, trade-ins, and other factors. Ask for the full written financing quote before making a decision.
How a Down Payment Can Help
A down payment reduces the amount you need to finance. For example, if a vehicle costs $18,000 before applicable taxes and fees and you contribute $3,000, the amount financed may be lower, subject to the final transaction details.
A larger down payment may improve affordability and reduce interest paid over the term. However, do not use all your emergency savings simply to reduce the loan. Part-time workers with fluctuating earnings may benefit from retaining enough cash to manage unexpected expenses or temporary reductions in shifts.
Banks vs. Dealerships vs. Brokers: Which Option Is Better?
Different financing channels may suit different applicants. No channel guarantees approval, and the best choice depends on the lender’s criteria, the available offers, and the full cost of the loan.
| Financing option | Potential advantages | What to check |
|---|---|---|
| Banks | Existing customer relationship and access to established lending products | Minimum income criteria, credit requirements, and available vehicle financing terms |
| Credit unions | Local service and products tailored to their membership | Membership eligibility, underwriting requirements, and fees |
| Dealership financing | Convenient applications while shopping for a vehicle; access to financing from participating providers | Total vehicle price, rate, fees, optional products, and whether the financing offer is competitive |
| Independent lenders | May offer alternatives for applicants who do not fit a particular bank’s criteria | Interest rate, lender reputation, contract terms, and total borrowing cost |
| Brokers | May help connect applicants with participating lenders | Broker compensation, lender options, credit-check process, and all applicable fees |
For flexible work auto financing Canada applicants, the most suitable provider is not necessarily the one that promises the easiest approval. Choose a provider that clearly explains its terms, evaluates your application transparently, and offers a repayment structure you can sustain.
Ask whether the provider is the lender or an intermediary, how it is compensated, and whether you can obtain a written quote before agreeing to proceed.
Practical Canadian Case Studies
The following fictional examples illustrate how lenders might assess different situations. They are not actual customer stories and do not represent guaranteed lending outcomes.
Case Study 1: A Retail Employee with Consistent Hours
Consider an applicant who works part-time in retail and receives approximately $2,100 per month after deductions. The applicant has consistent employment, manageable existing debt, and a record of paying credit obligations on time.
Rather than applying for the most expensive vehicle they can find, the applicant sets a conservative budget, prepares recent pay stubs, and compares financing offers. The lender still reviews the complete application, but the applicant can demonstrate a clear income history and a realistic repayment plan.
The lesson is that stable earnings, reasonable borrowing, and complete documentation may support an application even without full-time employment.
Case Study 2: Two Part-Time Jobs
Imagine an applicant earning $1,500 per month from a weekday job and $800 from weekend work. Both jobs are ongoing, and the applicant can provide separate pay stubs and bank records. part time income vehicle loans Canada
The applicant’s combined income is $2,300 per month before considering any differences between gross and net amounts. The lender must decide which income to recognize and how much weight to give it. The applicant should also calculate whether both jobs can realistically be maintained throughout the loan term.
This example shows why multiple income sources car loans Canada applicants should document every eligible income stream and avoid treating uncertain earnings as guaranteed.
Case Study 3: Seasonal Employment and an Expensive Vehicle
A third applicant earns good money during a busy season but experiences substantially lower earnings for several months each year. The applicant is considering a vehicle with a payment that would be difficult to manage during the quieter period.
Even if a lender is willing to consider the application, the applicant should evaluate the risks carefully. A smaller loan, a larger affordable down payment, or waiting until income is more predictable may be a safer approach.
The lesson is that getting approved and being able to afford the loan are two different things. Sustainable financing must work during ordinary months, not just the best earning periods.
Expert Tips to Strengthen Your Application
Keep Your Income Records Consistent
Use documents that clearly show your employment and earnings. If you receive income from several employers, prepare separate records for each. Clear documentation can make it easier for a lender to understand your financial situation. auto loan for part time workers Canada
Reduce Existing Financial Obligations Where Possible
Paying down high-interest debt may free up monthly cash flow and reduce the financial pressure of taking on another payment. Avoid closing accounts or making major credit decisions without considering the potential consequences for your circumstances.
Consider a More Affordable Vehicle
A less expensive vehicle may reduce the required loan amount and monthly payment. Focus on reliability, insurance costs, fuel efficiency, maintenance needs, and the length of time you expect to keep the car.
Save a Down Payment Without Sacrificing Your Emergency Fund
A down payment may reduce borrowing costs, but preserving some savings can be important when shifts or earnings are unpredictable. Choose an amount that supports both affordability and financial resilience.
Ask About Prequalification and Credit Checks
Some providers offer an initial assessment or prequalification process, but its meaning varies. Ask whether the result is conditional, whether a credit inquiry is required, and whether final approval depends on vehicle selection and document verification.
Compare the Complete Cost of Each Offer
Request written quotes and compare the interest rate, payment schedule, term, fees, total amount financed, and total amount payable. The Financial Consumer Agency of Canada recommends looking beyond monthly payments when evaluating vehicle financing.
Common Mistakes Part-Time Workers Should Avoid
Choosing a vehicle before setting a budget: Shopping based on the vehicle’s appearance or advertised payment can lead to borrowing more than you can comfortably afford.
Reporting unverified income: Inflating earnings or presenting occasional work as guaranteed income can undermine an application and may create serious problems.
Ignoring seasonal income changes: A payment that fits during a busy month may become difficult during a period of reduced shifts.
Focusing only on the interest rate: Fees, the loan term, optional products, and the amount financed all affect the total cost.
Accepting an unnecessarily long loan term: A longer term can increase interest costs and may leave you owing more than the vehicle is worth.
Submitting applications without comparing terms: Applying indiscriminately can create unnecessary credit inquiries and confusion. Understand each provider’s process before proceeding.
Draining emergency savings: Using every available dollar for a down payment may leave you unable to cover repairs, insurance, or essential expenses after a temporary income reduction.
Signing without reading the agreement: Confirm the final payment, term, rate, fees, and optional products in writing. Do not rely solely on verbal assurances.
Frequently Asked Questions
1. Can I get an auto loan for part-time workers in Canada without a full-time job?
Yes, it is possible. Some lenders consider part-time employees if they meet the lender’s requirements for income, credit, employment history, and affordability. A full-time position is not a universal requirement across all auto financing options. However, approval is not guaranteed, and individual lenders may impose minimum income or employment-history criteria. Prepare recent pay stubs, employment details, and a realistic budget before applying. auto loan for part time workers Canada
2. What is the minimum income required for a part-time car loan in Canada?
There is no single minimum monthly income that applies to every Canadian auto lender. A lender may consider your verified income alongside existing debts, housing expenses, credit history, down payment, and proposed loan amount. Someone with modest income and low expenses may have a different borrowing capacity from someone earning more but carrying substantial debt. Ask each prospective lender about its specific eligibility criteria rather than relying on a universal income figure.
3. Can I use income from two part-time jobs to qualify?
Potentially, yes. Some lenders may consider earnings from multiple jobs when the income is acceptable under their policies and can be verified. You may need pay stubs, employment letters, or bank statements from each employer. The lender may also consider how long you have held both positions and whether your work schedule appears sustainable. Disclose all income accurately and confirm which sources the lender will recognize before estimating your borrowing capacity. part time income vehicle loans Canada
4. Can I qualify for car financing if my hours change every week?
Variable hours do not automatically prevent you from qualifying. A lender may request several pay stubs or other evidence to evaluate your average earnings and income stability. If your income varies significantly, explain the pattern honestly and budget using a conservative estimate. Consider whether you could maintain payments during slower weeks or months. The lender’s decision will depend on its criteria and your complete financial profile.
5. Does a part-time job affect my auto loan interest rate?
It can affect the assessment if your employment pattern makes income less predictable, but part-time status alone does not determine your rate. Lenders may also consider credit history, debt obligations, the amount financed, vehicle details, and the proposed repayment term. Applicants with similar employment arrangements can receive different offers because their financial circumstances and lender criteria differ. Compare written quotes rather than assuming a particular rate based on employment status.
6. Can I get a car loan with part-time employment and limited credit history?
It may be possible, but fewer credit records can make it harder for a lender to assess your repayment history. Some providers may request additional documentation or offer different financing terms. Review your credit report, make existing payments on time, and avoid taking on unnecessary debt before applying. A down payment and a less expensive vehicle may help make the proposed loan more manageable, although neither guarantees approval.
7. Is a down payment necessary for part-time auto financing in Canada?
Not every lender or financing arrangement has the same down-payment requirements. Some applications may be considered without a down payment, while others may require one depending on the applicant, vehicle, loan amount, or lender policy. A down payment can reduce the amount financed and may lower total interest, but you should retain enough savings for emergencies. Confirm the specific requirements and final loan terms before purchasing the vehicle.
8. How can I improve my chances of approval before applying?
Start by checking your credit report, calculating reliable take-home income, reviewing existing debts, and setting a realistic vehicle budget. Gather recent pay stubs and employment confirmation, including records from additional jobs where applicable. Compare financing offers from more than one suitable provider, ask about credit-check procedures, and avoid overstating your income. Choose a loan that remains affordable if your hours temporarily decrease. No preparation can guarantee approval, but it can help you make a better-informed application.
Final Thoughts: Find Auto Financing That Fits Your Income
Working part-time does not automatically prevent you from financing a vehicle in Canada. The most important considerations are whether your income can be verified, whether your financial obligations are manageable, and whether the proposed payment fits your budget over the full loan term.
Before applying for an auto loan for part time workers Canada, gather your income records, review your credit report, calculate the complete cost of vehicle ownership, and compare written financing offers. If you earn money from more than one job, document each eligible income source and use realistic figures when estimating affordability.
At QuickApprovals.ca, start by exploring the auto financing information available for your situation and preparing the details a prospective lender may need. Ask questions about eligibility, interest, fees, and repayment terms before making a commitment.
The right financing decision is not simply about getting approved; it is about choosing a vehicle and repayment plan that you can manage confidently while protecting your long-term financial stability. flexible work auto financing Canada, qualify with part time job Canada, multiple income sources car loans Canada, flexible work auto financing Canada, part time income vehicle loans Canada
Suggested Internal Links for quickapprovals.ca
- Auto Loans in Canada: https://quickapprovals.ca/auto-loans/
- Car Loans in Canada: https://quickapprovals.ca/car-loans/
- Bad Credit Car Loans in Canada: https://quickapprovals.ca/bad-credit-car-loans/
- No Credit Car Loans in Canada: https://quickapprovals.ca/no-credit-car-loans/
- Used Car Loans in Canada: https://quickapprovals.ca/used-car-loans/
- Auto Loan Calculator Canada: https://quickapprovals.ca/auto-loan-calculator/
Suggested Authority Outbound References
- Financial Consumer Agency of Canada — Financing a Car: https://www.canada.ca/en/financial-consumer-agency/services/loans/financing-car.html
- Financial Consumer Agency of Canada — Shopping Around for Auto-Financing: https://www.canada.ca/en/financial-consumer-agency/services/loans/financing-car/shop-around.html
- Financial Consumer Agency of Canada — Car Financing Options: https://www.canada.ca/en/financial-consumer-agency/services/loans/financing-car/financing-options.html
- Financial Consumer Agency of Canada — What to Consider Before Borrowing Money: https://www.canada.ca/en/financial-consumer-agency/services/loans/consider-borrow.html
- TransUnion Canada — Credit Report and Credit Score Basics: https://www.transunion.ca/what-is-credit-report-and-credit-score
- Financial Consumer Agency of Canada — Financial Risks When Buying a Car: https://www.canada.ca/en/financial-consumer-agency/services/loans/financing-car/risks.html