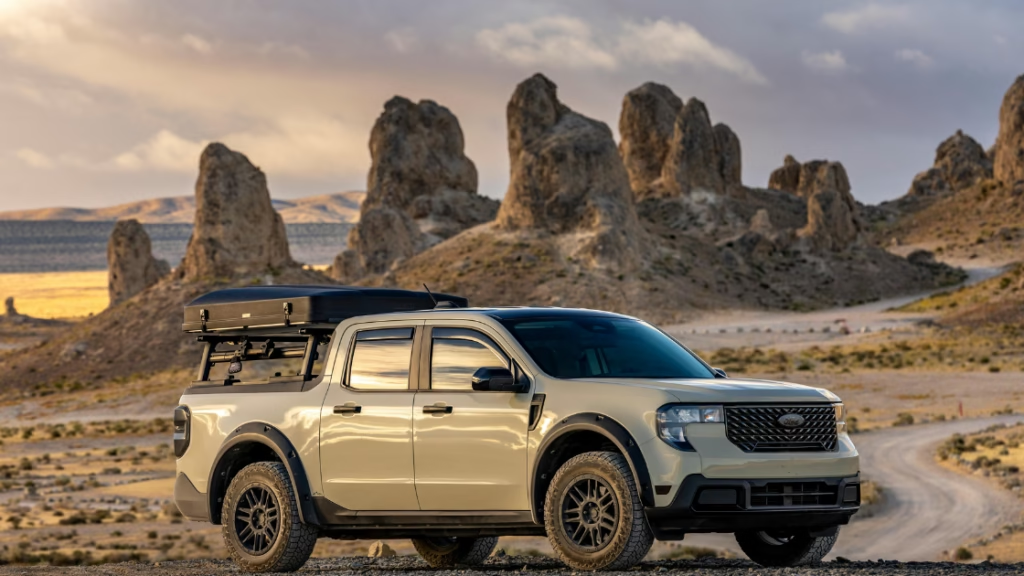
Buying a pickup truck in Canada is rarely just about choosing the right make, model, cab size, or towing capacity. For many buyers, the bigger challenge is arranging financing that fits both the vehicle and the household or business budget. A truck can be an essential work vehicle, a family vehicle, or both, but its higher purchase price means that even a small difference in the financing terms can significantly affect the total cost.
If you are researching pickup truck financing Canada, the goal should not simply be getting approved. The goal is understanding how much you are borrowing, what rate you are being offered, how long you will be making payments, and how much the truck will ultimately cost after interest and financing charges. The Financial Consumer Agency of Canada recommends comparing multiple financing offers and looking at the total borrowing cost rather than focusing only on the monthly payment.
This guide explains the financing process from application to approval, including best truck loan rates Canada considerations, work truck auto loans Canada, full size pickup financing Canada, and commercial truck car loans Canada. Whether you are buying a new pickup, used truck, work vehicle, or commercial-use truck, the following framework can help you compare your options more carefully.
Understanding pickup truck financing Canada before you apply
Pickup truck financing Canada refers to financing arrangements used to purchase a new or used pickup truck through a bank, credit union, dealership-arranged lender, independent finance company, or other financing provider. The financing structure can vary considerably depending on your credit history, income, vehicle, loan amount, down payment, and lender requirements.
A pickup truck is generally financed in much the same way as another motor vehicle, but the larger loan amounts commonly associated with trucks make budgeting particularly important. A $20,000 difference in vehicle price can produce a substantial difference in monthly payments and total interest. The same applies when you extend a loan term simply to reduce the monthly payment.
Canadian consumers can generally arrange vehicle financing through a dealership or directly with a financial institution. The Financial Consumer Agency of Canada notes that dealership financing can involve manufacturer financing divisions, banks, credit unions, and independent finance companies.
That means you do not necessarily have to accept the first financing offer presented at the dealership. Comparing alternatives before signing can give you a clearer picture of what the truck will actually cost.
How full size pickup financing Canada is evaluated
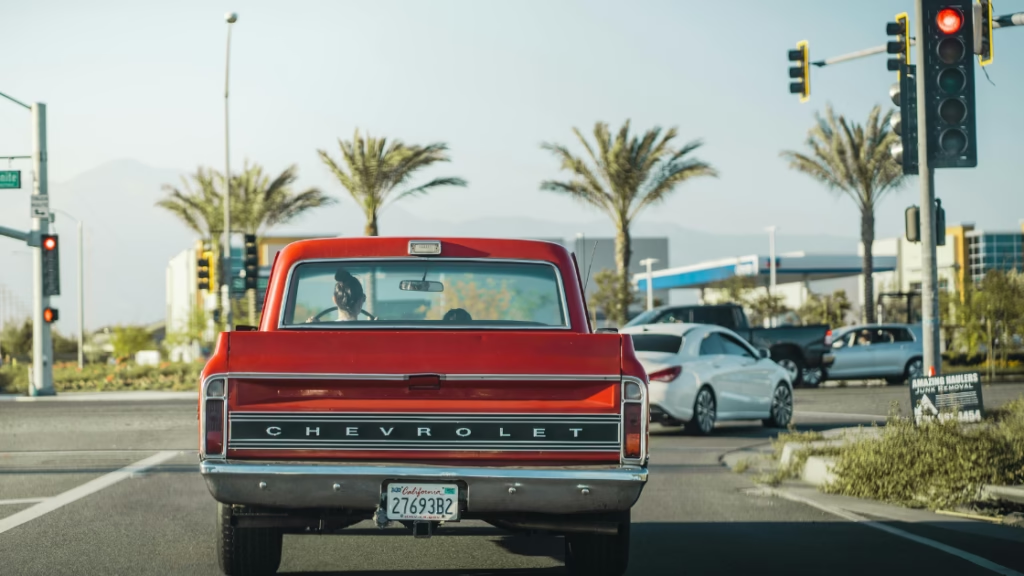
Full size pickup financing Canada can involve substantially more borrowing than financing a smaller passenger vehicle. A lender therefore has to consider whether the requested loan amount is reasonable relative to your income, existing debts, credit history, and the vehicle being financed.
Credit history is one consideration, but it is not the only one. Lenders may also evaluate employment or business income, debt obligations, residence information, down payment, vehicle age, purchase price, and the overall structure of the transaction. Different lenders can use different underwriting standards, so an application that does not fit one lender’s criteria may fit another lender’s requirements.
The vehicle itself also matters. A newer pickup with strong market value may be treated differently from an older high-mileage truck. Lenders want the financing to be supported by an asset whose value and condition are reasonably consistent with the amount being borrowed.
For borrowers, this means preparation matters. Before applying for full size pickup financing Canada, determine the purchase price you can realistically manage rather than beginning with the maximum amount a lender might approve.
What affects best truck loan rates Canada
There is no single rate that every Canadian truck buyer receives. Best truck loan rates Canada depend on the borrower, vehicle, lender, loan amount, term, and transaction structure.
Your credit profile can influence the rate offered to you. Stronger credit histories may qualify for more competitive conventional financing, while applicants with credit challenges may be offered different terms. Income stability and debt obligations can also affect the lender’s assessment.
The vehicle can influence financing as well. New and used pickups may have different lender programs, while promotional manufacturer financing can sometimes have specific eligibility requirements.
The wider interest-rate environment also matters, although the Bank of Canada’s policy rate is not the rate you personally pay on a truck loan. As of September 2, 2026, the Bank of Canada’s target overnight rate was 2.25%.
The Bank of Canada’s latest available monthly data in its published lending-rate series showed funds advanced for auto loans at 6.66% in July 2026. That is an aggregate statistical measure, not a guaranteed consumer offer or a quote for pickup truck financing.
For this reason, compare actual loan offers rather than assuming that a national average or advertised rate will apply to your situation.
Choosing work truck auto loans Canada for business use
Work truck auto loans Canada can be particularly important for contractors, tradespeople, service businesses, transportation operators, delivery businesses, and other professionals who depend on a pickup truck to generate income.
A work truck should be evaluated differently from a purely recreational purchase. The truck may produce economic value by allowing you to transport equipment, visit customers, reach job sites, tow trailers, or complete contracts. At the same time, the financing payment becomes a recurring business expense.
Before financing, estimate how the truck will affect your monthly cash flow. Include the loan payment, insurance, fuel, maintenance, registration, tires, repairs, and other operating expenses. Then compare those costs with the income or business activity the vehicle is expected to support.
For business borrowers, lenders may also request additional documentation. Depending on the lender and structure, that could include business information, income records, financial statements, banking information, or information about the vehicle’s intended use.
Commercial truck car loans Canada and business financing considerations
The phrase commercial truck car loans Canada can describe financing for vehicles used primarily for commercial purposes, although the actual financing structure may differ from a standard personal vehicle loan.
Commercial vehicle financing can involve consideration of both the vehicle and the business behind it. A lender may examine business history, revenue, existing obligations, credit information, vehicle value, down payment, and the purpose of the vehicle.
A newer business should not automatically assume financing is impossible. However, limited operating history can mean that the lender places greater importance on the owner’s personal financial profile, available documentation, down payment, and overall repayment capacity.
The most important distinction is to be accurate about how the vehicle will be used. Do not describe a commercial-use truck as personal-use transportation simply to try to qualify for different terms. Accurate information helps avoid documentation and underwriting problems later.
For buyers specifically interested in business vehicle financing, Quick Approvals also publishes a detailed guide covering Canadian commercial vehicle financing and approval considerations.
Step-by-step guide to pickup truck financing Canada
Step 1: Establish your realistic truck budget
Start with the total monthly cost rather than the truck’s advertised payment. Your budget should include financing, insurance, fuel, maintenance, registration, and other ownership expenses.
For example, a truck with a $900 loan payment may appear manageable until insurance, fuel and maintenance push the actual monthly transportation cost considerably higher.
Step 2: Check your financial position
Review your income, existing debts, credit obligations, and available down payment. Gather documents before submitting applications.
Typical information can include identification, address details, employment information, income documentation, vehicle details, purchase price, and down-payment information.
Step 3: Compare financing sources
Consider banks, credit unions, dealership financing, and independent financing providers. A dealership may arrange financing with multiple types of lenders, but you should still understand what alternatives are available.
FCAC specifically recommends obtaining quotes from multiple dealers and lenders and comparing the complete financing structure.
Step 4: Compare the complete offer
Do not compare payments alone. Review the interest rate, financing amount, fees, payment frequency, loan term, and total repayment amount.
A lower payment can simply mean a longer loan term.
Step 5: Confirm the vehicle details
Before finalizing financing, confirm the truck’s purchase price, taxes, fees, mileage, condition, vehicle identification information, and any optional products being financed.
Step 6: Read the agreement
Ask for the disclosure statement and loan agreement. Federally regulated financial institutions must provide important borrowing information, and consumers should review the total cost and terms before signing.
Eligibility requirements for pickup truck financing Canada
Eligibility varies between lenders, so there is no universal credit score or income requirement that guarantees approval.
However, borrowers should generally be prepared to provide:
- Government-issued identification
- Current address information
- Employment details
- Income information
- Existing debt information
- Vehicle make, model and year
- Purchase price
- Down-payment information
- Dealer or seller information
- Insurance information when required
For employed applicants, income verification may involve pay statements or employment information. Self-employed or business applicants may need additional documentation demonstrating income or business activity.
Credit history is also relevant. A lender may review payment history, existing obligations, credit utilization and other information contained in the credit application or credit report.
The amount being requested matters too. A $70,000 truck represents a significantly different lending exposure than a $25,000 used pickup, even if both borrowers have similar income.
Pickup truck financing Canada rates and cost breakdown
The following examples are illustrative calculations only. They are not advertised rates, guaranteed offers, or quotes from Quick Approvals.
| Amount Financed | Illustrative Rate | Term | Approx. Monthly Payment | Approx. Interest |
|---|---|---|---|---|
| $40,000 | 5.9% | 60 months | $771 | $6,287 |
| $45,000 | 6.66% | 60 months | $884 | $8,031 |
| $55,000 | 7.0% | 72 months | $938 | $12,514 |
| $65,000 | 8.0% | 84 months | $1,013 | $20,101 |
These examples demonstrate why best truck loan rates Canada should never be evaluated independently from the loan term. The $65,000 example has a lower monthly payment than a substantially shorter loan might produce, but the borrower pays more than $20,000 in interest over the illustrated 84-month repayment schedule.
Taxes and other financed charges can increase the amount borrowed. For example, if a $50,000 pickup has $6,500 in applicable sales taxes and the entire amount is financed, the loan principal could be $56,500 before considering other financed costs or a down payment.
That is why comparing only the advertised truck price can produce an incomplete picture.
Why longer terms can change full size pickup financing Canada
A longer repayment term can make a truck easier to fit into a monthly budget, but it generally increases the amount of time interest is charged.
Consider a simplified example. A buyer may be able to afford an $800 payment but not a $1,000 payment. Extending the term can reduce the monthly obligation, yet the borrower remains responsible for the debt for longer and may pay considerably more interest.
FCAC warns that longer vehicle loan terms can reduce payments while increasing the total amount of interest paid.
This becomes especially important with expensive pickups because the loan balance can remain substantial for years. If the truck depreciates faster than the loan balance declines, a borrower can face negative equity when attempting to sell or trade the vehicle.
Before selecting a long term, compare at least three figures:
- Monthly payment
- Total interest
- Total amount repaid
The third number is often the most revealing.
Banks vs lenders vs brokers for pickup truck financing Canada
| Financing Source | Typical Strength | Possible Consideration |
|---|---|---|
| Banks | Established financial relationship and conventional lending products | Credit and documentation requirements may be more restrictive |
| Credit Unions | Relationship-based lending and regional presence | Membership or eligibility requirements may apply |
| Dealership Financing | Convenient and integrated with vehicle purchase | The first offer may not represent the lowest available rate |
| Independent Lenders | May provide alternatives for different credit profiles | Terms and rates can vary considerably |
| Brokers | Can help compare financing across lender networks | Understand how the broker is compensated and what lenders are available |
There is no universal financing source that works best for every borrower. The important question is which available offer provides terms that fit your circumstances.
FCAC states that dealerships do not have to provide the lowest interest rate and recommends asking about multiple offers when possible.
A borrower with strong credit and an established banking relationship may receive an attractive offer directly from a financial institution. Another borrower may need a lender with different underwriting criteria. A broker can potentially provide access to multiple lenders through one application process, depending on the broker’s network.
Canadian case study: financing a personal pickup
Consider a hypothetical Ontario buyer purchasing a $52,000 pickup. The buyer has stable employment, good credit, and $7,000 available for a down payment.
Rather than beginning with a monthly payment target, the buyer compares the total purchase price, applicable taxes, financing amount, and loan term. The buyer obtains financing quotes from multiple sources before committing.
One lender offers a shorter term with a higher payment. Another offers a longer term with a lower payment. A third offer has a different interest rate and financing structure.
The buyer compares the total repayment amounts instead of selecting the lowest monthly figure automatically.
This approach illustrates the central principle of pickup truck financing Canada: affordability should be measured across the entire loan, not just the payment shown on a dealership worksheet.
Canadian case study: a contractor seeking work truck auto loans Canada
Imagine a self-employed contractor purchasing a $58,000 pickup for regular job-site use. The truck will transport tools and materials and is expected to remain in service for several years.
The contractor prepares income documentation, business information, existing debt details, and the vehicle purchase information before applying. Instead of asking only, “Can I get approved?”, the contractor also asks whether the payment remains manageable during slower business months.
The contractor compares a larger down payment against preserving cash for business operations. That distinction matters because putting every available dollar into the truck can reduce working capital.
The final financing decision should account for both vehicle affordability and business cash flow.
Canadian case study: commercial truck car loans Canada for a growing business
Consider a small service company that needs a pickup to support an expanding operation. The company has been operating for two years and has established revenue, but it wants to avoid using too much cash for the vehicle purchase.
The company compares financing structures and prepares documentation showing business revenue and repayment capacity. It also estimates fuel, insurance, maintenance and financing expenses.
Instead of treating the truck payment as an isolated expense, management evaluates the entire monthly vehicle cost against expected business cash flow.
This is a useful framework for commercial truck car loans Canada because the right financing structure should support operations rather than create unnecessary pressure on working capital.
How to improve your pickup truck financing Canada approval chances
Preparation can reduce unnecessary delays and make your application easier for a lender to evaluate.
First, keep your application information accurate and consistent. Differences between stated income, employment details and documentation can lead to additional verification.
Second, understand your existing debt before applying. A lender is not looking only at the new truck payment; existing obligations can affect overall repayment capacity.
Third, consider a reasonable down payment if you have sufficient cash available. A down payment reduces the amount financed, although you should avoid draining your emergency or operating reserves simply to reduce the loan.
Fourth, compare financing before entering the dealership when possible. Knowing your potential financing range can give you a reference point when reviewing dealer-arranged financing.
Finally, avoid submitting unnecessary applications indiscriminately. Ask the financing provider how its credit assessment works and whether the initial process involves a hard credit inquiry.
Quick Approvals also provides information about Canadian auto financing and preliminary credit-check considerations.
Common mistakes in full size pickup financing Canada
Choosing the payment instead of the loan
A $750 payment can look better than a $950 payment, but the $750 payment may involve a substantially longer term and higher total interest.
Ignoring the financed amount
Always confirm exactly how much you are borrowing after taxes, fees, trade-in adjustments and optional products.
Assuming advertised rates apply to everyone
Promotional rates may have eligibility requirements. Your actual financing offer can differ.
Financing unnecessary products
Loan insurance and other optional products can increase the cost of borrowing. FCAC notes that loan insurance is an optional product and that federally regulated financial institutions offering it must obtain express consent.
Focusing only on the truck price
The purchase price is only the starting point. Taxes, financing, insurance, fuel and maintenance all contribute to the cost of ownership.
Signing before reviewing the documents
FCAC advises consumers to review disclosure information and understand the financing terms before finalizing the agreement.
What to check before signing pickup truck financing Canada
Before signing, verify:
- Vehicle purchase price
- Down payment
- Trade-in value
- Amount financed
- Annual interest rate
- Payment amount
- Payment frequency
- Number of payments
- Loan term
- Total cost of borrowing
- Financing fees
- Optional products
- Insurance requirements
- Early-payment provisions
- Conditions relating to default
- Any other charges shown in the agreement
Federally regulated lenders must provide clear information about applicable loan terms and costs.
If something in the agreement differs from what you were told verbally, stop and ask for clarification before signing.
Frequently Asked Questions about pickup truck financing Canada
1. Can I get pickup truck financing Canada for a used truck?
Yes, used pickup trucks can be financed in Canada, although lender requirements can differ based on vehicle age, mileage, value, purchase price and borrower qualifications. A lender may impose restrictions on older or higher-mileage vehicles because the vehicle serves as collateral for the loan. Your credit profile, income, existing debt and requested amount can also affect the financing decision. Before purchasing a used pickup, obtain the vehicle’s complete purchase information and compare the financing terms with the truck’s expected useful life. A longer loan on an older vehicle deserves particular attention because you could still have loan payments after the vehicle has accumulated substantial mileage or depreciated significantly.
2. How do I find best truck loan rates Canada?
Start by obtaining actual financing offers rather than relying solely on advertised rates or general market averages. Compare banks, credit unions, dealership-arranged financing and other legitimate lenders available to you. Review the annual interest rate together with the loan term, amount financed, fees and total repayment amount. A lower rate can be valuable, but a longer term at that rate may still result in substantial total interest. FCAC recommends shopping around and comparing multiple offers before signing.
3. What are work truck auto loans Canada?
Work truck auto loans Canada are financing arrangements used to purchase pickups that serve employment or business purposes. The exact financing structure depends on the borrower and lender. A business-use vehicle may require additional documentation concerning business operations, income, ownership and intended vehicle use. If you are self-employed, prepare accurate financial information before applying. Do not assume that every commercial-use pickup must be financed through a specialized commercial product; ask the lender which financing structures are available for your particular situation.
4. Can I finance a large pickup with a longer loan term?
Potentially, depending on the lender, vehicle and borrower qualifications. A longer term reduces the scheduled payment by spreading repayment over more months, but it generally increases total interest. It can also increase the period during which you owe money on a depreciating asset. FCAC specifically warns consumers that longer vehicle loan terms can result in greater interest costs. Before choosing a long term, compare total repayment amounts and consider how long you expect to keep the truck.
5. Is full size pickup financing Canada more expensive than financing a smaller vehicle?
It can be more expensive in absolute dollars because full-size pickups often have higher purchase prices and therefore larger loan amounts. However, the actual interest rate depends on the borrower’s circumstances, lender, vehicle, term and financing structure. A larger loan at a competitive rate can sometimes have a lower rate than a smaller loan offered to a higher-risk borrower. Focus on the complete financing offer rather than assuming vehicle size alone determines the interest rate.
6. Can a business qualify for commercial truck car loans Canada?
A business may qualify for commercial vehicle financing depending on its financial circumstances and the lender’s criteria. Lenders can consider business history, revenue, existing obligations, credit information, vehicle value, down payment and intended use. Newer businesses may have fewer financial records available, which can make documentation especially important. Be prepared to explain why the vehicle is needed and how its financing will be supported by business cash flow.
7. Should I use dealership financing or a bank?
Both can be legitimate financing routes. Dealership financing is convenient because the dealer can often arrange the loan as part of the vehicle purchase. Direct financing through a bank or credit union can give you another offer to compare. FCAC explains that dealerships may arrange loans through manufacturer financing divisions, banks, credit unions or independent finance companies. Rather than assuming one channel is always cheaper, compare the actual interest rate, amount financed, term, fees and total repayment amount.
8. What should I do before signing a truck loan?
Review the complete financing agreement and disclosure statement. Confirm the vehicle price, taxes, down payment, trade-in, amount financed, interest rate, payment schedule, term, fees, optional products and total cost. Make sure the written agreement matches the terms you discussed. In most provinces and territories, there is generally no automatic cooling-off period for a vehicle loan or lease, so consumers should be ready to proceed before signing.
Final checklist for pickup truck financing Canada
Before submitting your application or signing your truck financing agreement, make sure you can answer these questions clearly:
- What is the total purchase price?
- How much am I putting down?
- How much am I actually financing?
- What interest rate am I being offered?
- How long is the loan?
- What is the total amount I will repay?
- What fees and optional products are included?
- Can I comfortably afford the payment alongside insurance, fuel and maintenance?
- Have I compared another financing offer?
- Does the written agreement match what I was promised?
These questions are particularly important when financing an expensive pickup because small differences in financing terms can translate into thousands of dollars over the life of the loan.
Start your pickup truck financing Canada research with the right numbers
Pickup truck financing Canada does not have to be complicated, but it should never be approached as a decision based solely on a monthly payment. The most useful starting point is a complete view of the purchase price, taxes, down payment, interest rate, loan term and total repayment cost.
Whether you need full size pickup financing Canada for family transportation, work truck auto loans Canada for your trade or business, or commercial truck car loans Canada for a growing operation, compare actual financing offers and make sure the payment fits your broader budget.
The Financial Consumer Agency of Canada recommends comparing financing options, understanding total borrowing costs and reviewing loan terms before signing. The Bank of Canada’s published lending statistics can provide useful market context, but individual financing offers depend on the borrower and transaction.
If you are ready to explore Canadian vehicle financing, you can begin with the Quick Approvals application process and provide your vehicle and financing requirements for review. Quick Auto Loan Approvals
Internal Links for QuickApprovals.ca
- Quick Approvals Home — Canadian Auto Financing
- Car Loan Calculator Canada
- Car Loan Payment Calculator Canada With Taxes
- Commercial Vehicle Loans Canada
- Car Loan Soft Credit Check Canada
- Car Loan Early Payoff Calculator Canada
Authority Outbound References
- Financial Consumer Agency of Canada — Financing a Car
- Financial Consumer Agency of Canada — Shopping Around for Auto-Financing
- Financial Consumer Agency of Canada — Car Financing Options
- Financial Consumer Agency of Canada — Car Loan Consumer Protections
- Bank of Canada — Interest Rates for New and Existing Lending
- Bank of Canada — Policy Interest Rate