Buying a used vehicle can make your budget go further, but the financing decision can determine whether you actually save money. A lower sticker price does not automatically mean a lower overall cost if the loan carries a higher interest rate, a long repayment term or additional financing fees. That is why understanding used car loan rates Canada 2026 before visiting a dealership can make a meaningful difference to the total amount you pay.
For Canadian borrowers, current market conditions provide useful context. Bank of Canada data for June 2026 shows that the average rate on funds advanced for auto loans by chartered banks was 6.55%, while the rate on outstanding auto-loan balances was 6.83%. These figures are broad banking-market statistics, not guaranteed rates for individual used-car buyers. Your actual offer can vary substantially according to credit history, income, vehicle age, loan amount, term and lender. used car loan rates Canada 2026
The practical objective is therefore not simply to find a headline rate. It is to understand financing used vehicles rates Canada, compare the complete borrowing cost, prepare a strong application and choose a vehicle and repayment term that fit your finances. This guide explains how used car loan rates Canada 2026 work, what affects your APR, how to compare lenders and how to avoid common financing mistakes.
What Are Used Car Loan Rates in Canada in 2026?
Used car loan rates Canada 2026 are the annual interest rates charged when you borrow money to purchase a pre-owned vehicle. Unlike a single advertised market rate, your actual rate is normally determined through underwriting. A lender may consider your credit history, income, employment or other qualifying information, the amount requested, the vehicle being financed and the proposed repayment period.
Bank of Canada statistics provide a useful market reference rather than a personal quote. In June 2026, the average rate on newly advanced auto loans reported by Canadian chartered banks was 6.55%. That does not mean every used vehicle purchaser will receive 6.55%. A borrower with strong credit and stable income may receive a different offer from someone with limited credit history or previous payment problems. used car loan rates Canada 2026
When evaluating best used auto loan APRs Canada, remember that APR and the nominal interest rate are not always interchangeable in the way consumers assume. The contract should clearly identify the borrowing rate and applicable costs. The Financial Consumer Agency of Canada recommends comparing the interest rate, payment schedule, financing fees, total amount financed and loan length rather than judging an offer by the monthly payment alone.
For borrowers researching pre-owned car financing options Canada, the most useful question is therefore: “What will this specific loan cost me from the first payment to the final payment?” That approach gives you a more accurate picture than relying on a generic rate advertised online. used car loan rates Canada 2026
Why Used Vehicle Financing Rates Can Differ
Used vehicle financing rates Canada can differ because lenders evaluate both the borrower and the collateral. A newer used vehicle may have a different lending profile from an older vehicle with significantly higher mileage. Similarly, a borrower with established credit and consistent income may receive different terms from someone whose credit file contains recent late payments. used car loan rates Canada 2026
The vehicle itself matters because its age, condition, value and eligibility can influence the lender’s risk assessment. The requested loan amount also matters. A larger amount can produce a higher total interest cost even when the rate remains unchanged. The repayment period is equally important because stretching the balance over more months generally reduces the scheduled payment but increases the amount of interest paid.
Your financial profile is another major component of compare used car loan rates Canada. Credit reports contain information about credit accounts and payment history, and lenders may use credit information alongside other factors when assessing an application. TransUnion Canada notes that credit reports are commonly used in decisions involving auto loans and that credit information can influence lending decisions.
That is why two Canadians buying similar vehicles at similar prices can receive different financing offers.
2026 Market Context for Used Car Financing
used car loan rates Canada 2026 should be considered within the broader Canadian borrowing environment. The Bank of Canada publishes lending-rate data from chartered banks, allowing consumers to see how auto-loan pricing has been moving across the banking sector.
As of June 2026, the Bank of Canada reported 6.55% for funds advanced under its auto-loan category and 6.83% for outstanding auto-loan balances. These statistics describe bank lending activity across borrowers and should not be interpreted as a guaranteed used-car rate.
For someone researching financing used vehicles rates Canada, this distinction is important. A market average is useful for context, but an actual financing offer depends on individual underwriting. It is also possible for a dealership, bank, credit union or independent finance company to present different offers to the same borrower.
The Financial Consumer Agency of Canada confirms that Canadians may obtain vehicle financing through dealerships, financial institutions and independent finance companies.
The most sensible way to use market data is therefore as a reference point while comparing personalized offers.
Used Car Loan Rate Examples for 2026
used car financing cost Canada becomes easier to understand when you see the mathematics. Consider a hypothetical $25,000 loan over 60 months with no additional fees. The following examples are illustrative calculations, not guaranteed offers: best used auto loan APRs Canada
| Annual Rate | Approx. Monthly Payment | Approx. Total Interest | Approx. Total Payments |
|---|---|---|---|
| 5.00% | $471.78 | $3,306.85 | $28,306.85 |
| 6.55% | $489.74 | $4,384.36 | $29,384.36 |
| 9.00% | $518.96 | $6,137.53 | $31,137.53 |
| 12.00% | $556.11 | $8,366.67 | $33,366.67 |
These calculations demonstrate why best used auto loan APRs Canada matter. A difference in interest rate can translate into thousands of dollars over a five-year repayment period.
The example also shows why focusing exclusively on the monthly payment can be misleading. A borrower might accept a longer term because it produces a lower monthly obligation, but the additional months can substantially increase total interest. FCAC specifically warns that longer car-loan terms can reduce payments while increasing total borrowing costs. best used auto loan APRs Canada
How to Compare Used Car Loan Rates Canada
compare used car loan rates Canada by keeping the variables consistent. If one lender quotes a $25,000 loan over 60 months and another quotes $25,000 over 84 months, comparing only the monthly payments does not provide a meaningful comparison. pre-owned car financing options Canada
Request the same information from each financing source: compare used car loan rates Canada
- Annual interest rate
- Payment frequency
- Loan term
- Amount financed
- Financing or administration fees
- Total borrowing cost
- Conditions attached to the approval
- Prepayment terms
- Any optional products included in the contract
For pre-owned car financing options Canada, compare offers using the same vehicle price, down payment and repayment period whenever possible.
FCAC recommends obtaining quotes from multiple dealers and lenders and comparing the complete terms of each offer. It also notes that a dealership does not necessarily have to provide the lowest available interest rate. compare used car loan rates Canada
This makes independent comparison particularly valuable before signing a vehicle purchase agreement. pre-owned car financing options Canada
Banks vs Lenders vs Brokers for Used Car Financing
used vehicle financing options Canada can come through several channels. Each has a different role in the financing process. used car loan rates Canada 2026
| Financing Source | Typical Strength | What to Check |
|---|---|---|
| Banks | Established lending relationship and conventional underwriting | Eligibility, rate, vehicle requirements |
| Credit Unions | May offer relationship-based financing | Membership requirements and terms |
| Dealership Financing | Convenient because financing occurs during vehicle purchase | Whether multiple lenders were considered |
| Independent Lenders | May serve borrowers outside traditional bank criteria | Rate, fees and contract conditions |
| Financing Brokers | Can help connect borrowers with multiple financing sources | Which lenders are accessed and how the offer is structured |
The right comparison is not necessarily “bank versus broker” or “dealer versus lender.” The useful comparison is the actual written financing offer.
For borrowers exploring financing used vehicles rates Canada, convenience should not replace due diligence. FCAC confirms that dealerships may arrange financing through manufacturer financing divisions, financial institutions such as banks and credit unions, and independent finance companies.
Step-by-Step Guide to Getting a Used Car Loan in Canada
Step 1: Establish Your Vehicle Budget
used car loan affordability Canada starts before the application. Calculate how much you can comfortably allocate toward the vehicle after considering insurance, fuel, maintenance, registration and other household expenses.
Do not build your budget around the maximum payment a lender says you can afford. Build it around an amount that remains manageable if your expenses increase.
Step 2: Check Your Credit Information
used car loan credit requirements Canada are easier to understand when you know what is actually contained in your credit file. Review your credit report before applying and check for inaccurate information, unfamiliar accounts or reporting issues.
TransUnion explains that lenders may use credit reports and scores as part of decisions involving auto loans and other credit products.
Step 3: Gather Your Documents
used car loan approval requirements Canada can vary between lenders, but applicants may commonly need identification, proof of income, employment information, residential details and vehicle information.
Having accurate documents ready can reduce delays and help ensure that the information on your application matches the supporting paperwork.
Step 4: Seek Financing Before Finalizing the Vehicle
used car financing pre-approval Canada can help establish a realistic borrowing range before you negotiate a vehicle purchase. It can also make it easier to compare a dealer’s financing proposal against another available offer.
A pre-approval or preliminary decision is not necessarily identical to final funding. Final terms may depend on verification of the borrower and vehicle.
Step 5: Compare the Complete Loan
compare used car loan rates Canada using the rate, term, fees and total cost rather than payment size alone.
Ask what happens if you make additional payments, pay the loan early or refinance later. Read the financing agreement carefully before signing.
Step 6: Confirm the Vehicle Details
used vehicle loan eligibility Canada can depend partly on the vehicle. Age, mileage, purchase price and other lender criteria may affect whether the vehicle qualifies and on what terms.
Make sure the vehicle information on the financing paperwork matches the actual vehicle you are purchasing.
Step 7: Review the Final Contract
used car loan contract Canada should be reviewed line by line. Check the interest rate, amount financed, payment schedule, term, fees and optional products.
FCAC states that lenders or dealers must provide a disclosure statement explaining important borrowing-cost information before the agreement is finalized in circumstances covered by applicable consumer-protection rules.
Eligibility and Requirements for Used Car Financing
used car loan eligibility Canada is not based on one universal credit-score cutoff. Different lenders use different underwriting models and may consider several elements of the application.
Common factors can include:
- Credit history and payment behaviour
- Income and employment
- Existing debts
- Down payment
- Loan amount
- Vehicle price and characteristics
- Loan term
- Residential and identification information
- Overall application profile
A strong credit history can make it easier to qualify for competitive best used auto loan APRs Canada, but a less-established or damaged credit profile does not automatically mean financing is impossible. It may instead affect the lender pool, rate or other terms available.
The key is to avoid assuming that a single credit score tells the entire story. Lenders can use credit information alongside income, debt obligations, vehicle information and their own lending criteria.
What Can Help You Get a Lower Rate?
lower used car loan rates Canada are generally easier to pursue when the application presents lower perceived lending risk. You cannot control every factor, but several elements can be prepared in advance. used car loan rates Canada 2026
Consider:
- Improving credit payment history: Consistent on-time payments can strengthen your credit profile over time.
- Reducing revolving debt: Lower outstanding balances may improve your overall financial position.
- Making a down payment: Borrowing less reduces the principal and can lower the total interest paid.
- Choosing a reasonably priced vehicle: A smaller loan can make the entire transaction easier to manage.
- Comparing several offers: Shopping around can reveal differences between lenders.
- Choosing an appropriate term: A shorter term can reduce total interest when the payment remains affordable.
- Preparing accurate documentation: Complete information can help prevent avoidable application delays.
These strategies do not guarantee a particular APR. They are practical ways to improve the quality of your financing comparison.
Practical Canadian Case Study: Strong Credit Profile
competitive used car financing Canada can be illustrated through a hypothetical borrower purchasing a $25,000 used vehicle. Suppose the borrower has stable income, established credit and enough savings for a modest down payment.
If the borrower finances $22,500 for 60 months at a hypothetical 6.55%, the payment is approximately $441 per month before any applicable fees or taxes incorporated into the actual contract. Compared with borrowing the entire $25,000, the lower principal reduces both the scheduled payment and total interest.
The lesson is not that every borrower should target 6.55%. That number is used only because the Bank of Canada reported it as the June 2026 average rate for funds advanced under its auto-loan category. Individual offers can differ.
Practical Canadian Case Study: Higher-Rate Financing
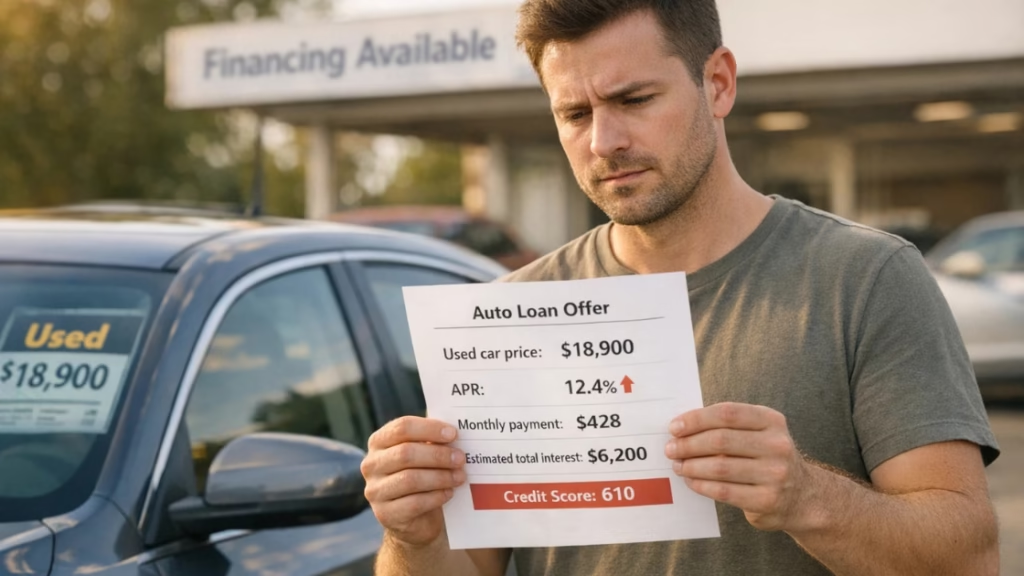
used car loan rates for credit challenges Canada can look very different from mainstream bank averages. Imagine another borrower purchasing a $25,000 vehicle but receiving a hypothetical 12% rate over 60 months.
The approximate payment would be $556 per month, with approximately $8,367 in interest over the term, assuming a simple fixed-rate amortizing loan and no additional fees. This example demonstrates why comparing financing offers matters particularly when the rate is higher.
The borrower should also consider whether a less expensive vehicle, larger down payment or shorter financing amount could improve affordability. The goal should be to understand the complete cost before accepting the contract rather than concentrating only on whether an approval is available.
How Loan Term Changes Your Total Cost
used car loan term Canada is one of the most important variables in financing. A longer term can reduce the required monthly payment, but it generally increases the amount of interest paid. financing used vehicles rates Canada
FCAC provides an illustrative comparison in which a $25,000 loan at 5% costs approximately $26,974 over 36 months but approximately $29,681 over 84 months. The difference is $2,707 in total cost.
Long terms can also create negative-equity risk. If the vehicle depreciates faster than the loan balance declines, you could owe more than the car is worth when you want to sell or trade it. FCAC specifically highlights this risk with long-term vehicle financing.
For financing used vehicles rates Canada, this matters because a used vehicle is already partway through its depreciation cycle. The relationship between the vehicle’s value and outstanding loan balance deserves careful attention.
Expert Tips to Speed Up Used Car Loan Approval
fast used car loan approval Canada is usually easier when the application is complete and consistent from the beginning. used car loan rates Canada 2026
Prepare identification, proof of income and other documents before submitting an application. Verify your employment information, residential details and requested loan amount. If a lender requests clarification, respond promptly.
Avoid submitting inaccurate information simply to obtain an approval. A discrepancy between an application and verification documents can create additional delays.
It is also useful to know the vehicle’s exact year, make, model, mileage, purchase price and seller information before the financing process reaches the final stage.
Digital applications can simplify the initial process, but final approval and funding may still require documentation and vehicle verification. The speed of the application should therefore never be confused with the quality or affordability of the financing.
Critical Mistakes to Avoid
used car loan mistakes Canada can be expensive because financing decisions last for years rather than days.
Focusing Only on Monthly Payments
A low payment can result from a long term rather than a low borrowing cost. Always calculate the total amount paid.
Accepting the First Financing Offer
The first offer may not represent every financing option available to you. FCAC recommends shopping around and comparing multiple offers.
Ignoring Fees
A slightly lower interest rate may not produce the lowest overall cost if additional fees are included. Review the complete disclosure.
Financing Too Much Vehicle
A lender’s approval limit is not necessarily your personal budget. Leave room for insurance, maintenance, fuel and unexpected expenses.
Choosing an Excessively Long Term
Longer terms can increase total interest and create negative-equity risks.
Signing Before Reviewing the Contract
Do not rush through the paperwork. Verify the rate, term, amount financed, payment schedule and optional products before signing.
Frequently Asked Questions About Used Car Loan Rates Canada 2026
What are used car loan rates in Canada in 2026?
used car loan rates Canada 2026 vary by borrower, lender and vehicle. The Bank of Canada reported an average 6.55% rate for funds advanced under its auto-loan category by chartered banks in June 2026. This is a market-level statistic, not a guaranteed rate for used vehicles or an individual applicant. Your actual offer can differ based on credit history, income, vehicle details, loan amount and term.
What is considered a competitive used car loan APR?
best used auto loan APRs Canada depend on the individual borrower and financing circumstances. There is no single APR that qualifies as competitive for every applicant. Compare personalized offers using the same loan amount and term, then examine interest, fees and total borrowing cost. Market averages can provide context, but they should not be treated as promises.
Can I compare used car financing from a bank and dealership?
Yes. compare used car loan rates Canada by requesting comparable written offers from different financing sources. FCAC explains that car financing may be arranged through dealerships, banks, credit unions and independent finance companies. A dealership’s financing offer does not automatically represent the lowest available rate, so comparison can be worthwhile.
Does my credit score affect used-car loan rates?
used car loan credit requirements Canada can include credit information, although lenders may consider more than a score. Credit history, payment behaviour and other information on a credit report can contribute to lending decisions. TransUnion states that credit reports are commonly used for auto-loan decisions and that lenders may use credit information when assessing risk.
Is a longer used-car loan term better because the payment is lower?
used car loan term Canada should be selected based on affordability and total cost rather than payment alone. A longer term generally reduces the scheduled payment but increases the period over which interest accumulates. It can also increase the possibility of owing more than the vehicle is worth. FCAC recommends understanding these risks before accepting long-term vehicle financing.
What documents are needed for used-car financing?
used car loan approval requirements Canada vary by lender. Applicants may be asked for identification, income or employment information, residential details and vehicle information. Having accurate documents ready can make verification smoother. If your application involves unusual income, multiple income sources or credit challenges, additional documentation may be requested.
Can I get financing for a used vehicle with credit challenges?
used car financing options Canada can include different lender categories, and eligibility depends on the lender’s criteria. A borrower with credit challenges may face fewer options or a higher rate than someone with stronger credit. Before accepting a higher-cost loan, compare the payment, total interest, fees, vehicle price and term to make sure the complete transaction remains affordable.
Should I get financing before choosing my used vehicle?
pre-owned car financing options Canada can be easier to evaluate when you understand your financing range before negotiating the vehicle. Preliminary approval can help you establish a realistic budget and compare a dealer’s offer with other financing options. Remember that a preliminary approval is not necessarily final funding; the lender may still need to verify your information and the vehicle.
Final Checklist Before Signing a Used Car Loan
Before accepting used car loan rates Canada 2026, verify all of the following:
- Vehicle purchase price
- Down payment
- Amount financed
- Interest rate
- Payment frequency
- Loan term
- Total interest
- Total borrowing cost
- Financing and administration fees
- Optional products
- Prepayment conditions
- Vehicle information
- Insurance requirements
- Final contract and disclosure documents
The Financial Consumer Agency of Canada recommends looking beyond the payment and considering the total cost of the vehicle, including interest and other ownership expenses.
Conclusion: Make Your 2026 Used-Car Financing Decision With the Full Cost in View
Understanding used car loan rates Canada 2026 is about more than finding a percentage advertised online. Current Bank of Canada data gives borrowers useful market context, with 6.55% reported for funds advanced under the auto-loan category by chartered banks in June 2026. But your personal financing offer can be higher or lower depending on your credit profile, income, vehicle and loan structure.
The strongest approach is straightforward: establish your budget, review your credit information, compare financing used vehicles rates Canada, request comparable offers, examine the complete cost and read the contract before signing. If you are evaluating pre-owned car financing options Canada, remember that the lowest monthly payment is not necessarily the lowest-cost loan.
Quick Approvals can be a starting point for Canadians researching vehicle financing and comparing their available options. Before committing, use the information in your financing agreement—not an advertised rate—as the final source for your actual borrowing cost.
Suggested Internal Links for QuickApprovals.ca
- https://quickapprovals.ca/car-loan-calculator-canada/
- https://quickapprovals.ca/car-loan-calculator-with-taxes-canada/
- https://quickapprovals.ca/online-car-loan-approval-process-canada/
- https://quickapprovals.ca/fast-car-loan-funding-canada/
- https://quickapprovals.ca/high-mileage-used-car-loan-tips/
- https://quickapprovals.ca/auto-loan-with-low-monthly-payments-canada/
Suggested Authority Outbound References
- Financial Consumer Agency of Canada — Financing a Car
- Financial Consumer Agency of Canada — Shopping Around for Auto-Financing
- Financial Consumer Agency of Canada — Financial Risks When Buying a Car
- Bank of Canada — Interest Rates for New and Existing Lending
- TransUnion Canada — Credit Report and Credit Score Information
- Government of Canada — Vehicle Lease or Loan Calculator