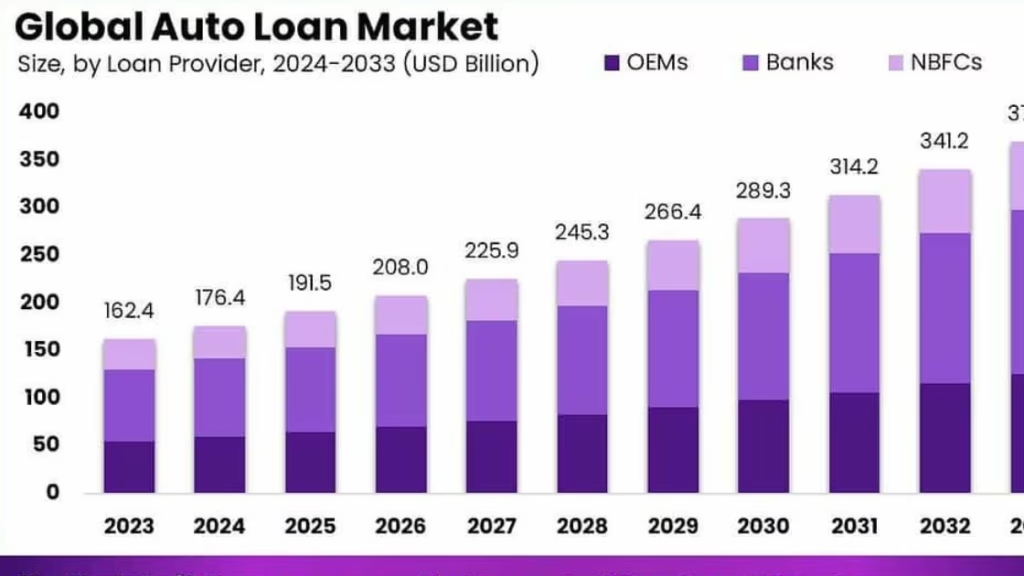
Canada’s vehicle-financing market is entering 2026 with a very different set of conditions than borrowers faced during the rapid rate increases of previous years. The Bank of Canada has held its policy interest rate at 2.25% since October 2025, including its September 2, 2026 decision. At the same time, inflation, energy prices, trade uncertainty and household debt remain important variables for lenders and consumers.
For anyone researching the auto loan market outlook 2026 Canada, the important question is not simply whether car-loan rates will rise or fall. The bigger issue is how lenders may respond to changing economic conditions, borrower risk, vehicle prices and demand. Statistics Canada reported 176,156 new motor vehicles sold in July 2026, down 2.0% year over year by unit volume, while dollar sales increased 1.6%. Zero-emission vehicle sales, meanwhile, rose 36.0% year over year.
That combination creates a market where opportunities and risks can exist at the same time. Borrowers with strong credit and stable income may have more financing choices, while applicants with weaker credit or inconsistent income may face closer underwriting. Understanding Canadian auto lending trends 2026 Canada can help you prepare before applying rather than reacting after a lender has already assessed your application. auto loan market outlook 2026 Canada
Canadian auto lending trends 2026 Canada: What Is Changing?
The Canadian auto lending trends 2026 Canada story is being shaped by several forces at once: borrowing costs, household debt, vehicle affordability, digital applications, credit risk and changing vehicle preferences. The Financial Consumer Agency of Canada confirms that Canadians can arrange vehicle financing through dealerships, banks, credit unions and independent financing companies. That means consumers are not limited to a single financing channel when purchasing a vehicle.
The market is also becoming increasingly data-driven. Lenders can assess income, credit history, existing obligations, vehicle characteristics and other risk factors when determining financing terms. For borrowers, this means the headline interest rate advertised online may not be the rate ultimately offered on an individual application. auto loan market outlook 2026 Canada
Current credit-market data reinforces the importance of affordability. TransUnion reported that Canadian consumer debt reached $2.64 trillion in Q2 2026, with outstanding balances up 4.6% year over year. It also reported that more Canadians were seriously behind on payments compared with the previous year, with stress concentrated particularly in Alberta, Saskatchewan and Ontario. Canadian auto lending trends 2026 Canada
These conditions can encourage lenders to balance loan growth with risk management. A borrower who wants to benefit from the auto loan market outlook 2026 Canada should therefore focus on the complete financing profile rather than assuming that a lower central-bank rate automatically means every borrower will receive a cheaper car loan. Canadian auto lending trends 2026 Canada
expected rate movements Canada: How Interest Rates Could Affect Auto Loans
The most closely watched part of the expected rate movements Canada discussion is the Bank of Canada policy rate. As of September 2, 2026, the overnight target remains 2.25%. The Bank has said inflation risks have increased, while new tariffs and geopolitical developments have created additional uncertainty around growth. auto loan market outlook 2026 Canada
The Bank of Canada’s July 2026 Monetary Policy Report projected real GDP growth of 0.7% for 2026 and 1.8% for both 2027 and 2028. Its July projection also expected CPI inflation to average approximately 2.5% in 2026 and 2.0% in 2027. These are economic projections, not forecasts of individual auto-loan rates. expected rate movements Canada
Market participants surveyed by the Bank of Canada in Q2 2026 had a median policy-rate expectation of 2.25% for the remainder of 2026, with the median rising to 2.50% in several 2027 survey periods. The same survey showed that 40% of respondents viewed the risks around their rate forecast as skewed toward a higher path, compared with 28% toward a lower path and 32% as broadly balanced. expected rate movements Canada
For an auto-loan borrower, the practical lesson is straightforward: do not build a vehicle budget around the assumption that rates will definitely decline. Expected rate movements Canada can influence broader borrowing conditions, but the rate offered on a car loan depends on the lender, borrower, vehicle, loan amount, term and credit profile.
volume and delinquency forecast Canada: What Credit Data Suggests
The volume and delinquency forecast Canada picture is closely connected to household affordability. When consumers carry larger balances while facing higher living costs, lenders have to consider whether monthly obligations remain sustainable. TransUnion’s Q2 2026 report showed total consumer debt increasing faster than the number of Canadians with access to credit, indicating that existing borrowers were carrying larger balances than a year earlier.
Auto finance is particularly sensitive to this environment because a vehicle is both a necessary household asset and a significant recurring expense. TransUnion reported that average balances increased across several credit products, including auto finance, even where origination volumes contracted. Its Q2 webinar reported a 4.3% year-over-year increase in average balances for mortgage and auto finance combined. volume and delinquency forecast Canada
This does not mean every Canadian borrower is facing rising delinquency risk. Credit performance differs by province, income, credit profile and loan structure. It does mean that borrowers should take volume and delinquency forecast Canada information seriously when determining how much vehicle debt they can comfortably carry.
A financially sustainable loan should remain manageable even if gasoline costs rise, income temporarily falls or other household expenses increase. The goal is not simply to qualify for the largest amount a lender will approve; it is to select financing that remains affordable throughout the loan term. volume and delinquency forecast Canada
How Vehicle Sales Could Influence the auto loan market outlook 2026 Canada
Vehicle demand is another major component of the auto loan market outlook 2026 Canada. Statistics Canada reported that July 2026 new motor vehicle sales declined 2.0% in units from July 2025, but the dollar value of sales increased 1.6%. New passenger-car sales fell 4.6%, while new truck sales fell 1.6%.
At the same time, zero-emission vehicles represented 10.7% of new motor vehicle sales in July 2026, compared with 7.7% a year earlier. That shift can affect financing demand because EV buyers may evaluate financing alongside charging costs, incentives, depreciation expectations and long-term ownership costs.
For borrowers, vehicle selection can matter almost as much as the interest rate. A lower-priced vehicle with a reasonable term may create a more sustainable payment than a higher-priced vehicle financed over a much longer period. The Financial Consumer Agency of Canada specifically recommends looking at total cost rather than focusing only on monthly payments or the interest rate.
Step-by-Step: How to Prepare for prepare for market shifts Canada
1. Review Your Credit Before Applying
The first step to prepare for market shifts Canada is understanding your current credit position. Canada’s Financial Consumer Agency explains that Canadians can obtain free credit reports from Equifax and TransUnion, and checking your own report does not affect your credit rating.
Review both reports for incorrect balances, unfamiliar accounts, missed-payment information or unauthorized inquiries. If an error exists, correcting it before a major financing application can prevent an avoidable problem. FCAC recommends checking both major credit bureaus because their records can differ. prepare for market shifts Canada
2. Establish a Realistic Vehicle Budget
Your budget should include the vehicle payment plus insurance, fuel or charging costs, maintenance, registration and other ownership expenses. A lender’s maximum approval is not necessarily the same as a financially comfortable payment.
For example, consider a hypothetical $30,000 amount financed over 60 months. At an illustrative 7.99% annual interest rate, the payment is approximately $608 per month and total interest is approximately $6,480. At an illustrative 11.99% rate, the payment rises to approximately $667 per month and total interest to approximately $10,000. prepare for market shifts Canada
| Illustrative Financing | Amount Financed | Rate | Term | Approx. Monthly Payment | Approx. Total Interest |
|---|---|---|---|---|---|
| Example A | $30,000 | 7.99% | 60 months | $608 | $6,480 |
| Example B | $30,000 | 11.99% | 60 months | $667 | $10,000 |
| Example C | $30,000 | 14.99% | 60 months | $714 | $12,840 |
These figures are examples for comparison only and are not advertised or guaranteed rates. Taxes, lender fees, optional products and other transaction costs can change the actual amount financed.
3. Compare More Than One Financing Channel
The Canadian auto lending trends 2026 Canada environment gives borrowers multiple possible routes. FCAC identifies dealerships, financial institutions and independent finance companies as potential sources of car financing. prepare for market shifts Canada
| Financing Channel | Potential Strength | What to Check |
|---|---|---|
| Bank | Established relationship and conventional lending | Rate, eligibility and loan conditions |
| Credit Union | Local/member-focused lending | Membership requirements and pricing |
| Dealership | Convenient vehicle purchase and financing together | Multiple lender offers and total cost |
| Independent Lender | May serve broader credit profiles | Rate, fees and repayment terms |
| Financing Broker | May compare financing sources | Compensation, lender options and final terms |
A dealership does not necessarily have to offer the lowest interest rate available. FCAC recommends getting quotes from multiple dealers and lenders and comparing the complete cost before signing.
Eligibility and Requirements in the 2026 Market
There is no single Canadian approval formula that applies to every lender. However, lenders commonly evaluate credit history, income, employment or income stability, existing obligations, requested loan amount, vehicle information and repayment capacity.
Typical documentation may include government-issued identification, proof of address, employment or income information, bank statements or tax documents where applicable, and vehicle details. Self-employed and variable-income applicants may need additional documentation demonstrating that income is genuine and sufficiently consistent.
A down payment can also change the financing structure. It reduces the amount borrowed and may reduce the loan-to-value relationship. However, using every dollar of available savings as a down payment is not necessarily appropriate if it leaves no emergency reserve.
Applicants should also understand that approval and affordability are different concepts. A lender may determine that a particular loan meets its underwriting criteria while the borrower may still find the payment uncomfortable after considering household expenses.
Comparing Banks, Lenders and Brokers
The auto loan market outlook 2026 Canada is not just about interest rates. Financing channels can differ in speed, documentation, credit-policy flexibility and product selection.
| Factor | Banks | Independent Lenders | Brokers |
|---|---|---|---|
| Application channel | Branch or digital | Often digital | Often digital |
| Credit profiles | Usually policy-driven | May serve broader profiles | Depends on lender network |
| Vehicle financing | Yes | Yes, depending on lender | Arranges through participating lenders |
| Rate comparison | Usually own products | Usually own products | May compare multiple sources |
| Documentation | Varies | Varies | Depends on selected lender |
| Convenience | Established process | Often streamlined | One application may access multiple options |
The correct comparison is the actual offer you receive, including annual interest rate, total interest, term, fees, optional products and conditions.
Practical Canadian Case Studies
Case Study 1: Strong Credit and Stable Employment
A borrower with stable employment, established credit and a $35,000 vehicle budget may have access to conventional bank, credit-union, dealership or manufacturer financing. In this situation, comparing offers can be particularly useful because a modest rate difference can produce meaningful savings over several years.
Case Study 2: Variable Income
A borrower whose income changes from month to month may still qualify for financing, but documentation becomes particularly important. Recent income records, tax documents, contracts and bank statements can help establish the broader income picture. The borrower should also select a payment that remains manageable during weaker-income months.
Case Study 3: Challenging Credit
A borrower with previous late payments may face fewer conventional options or a higher quoted rate. Canada’s credit system allows lenders to consider credit history when assessing applications, and negative information can affect access to credit and interest rates.
In this situation, the borrower should compare the complete financing cost rather than accepting the first approval. A less expensive vehicle, larger practical down payment or improved credit profile may change the available financing structure.
Approval Acceleration Tips for prepare for market shifts Canada
Borrowers who want to prepare for market shifts Canada can make their applications easier to evaluate by preparing documentation before submitting an application.
- Check both credit reports.
- Correct obvious reporting errors.
- Calculate a realistic monthly vehicle budget.
- Gather identification and income documents.
- Know your existing monthly debt obligations.
- Decide whether a down payment is financially practical.
- Compare financing offers from more than one source.
- Review the total borrowing cost rather than payment alone.
- Confirm the vehicle price separately from financing.
- Read the disclosure statement before signing.
FCAC advises consumers to compare prices, negotiate where possible, consider depreciation and negative equity, understand long-term loan risks and review related ownership expenses such as insurance and fuel.
Critical Mistakes to Avoid
The biggest mistake in a changing market is assuming that the lowest advertised payment represents the lowest-cost financing. Extending a loan can reduce the monthly payment while increasing the total interest paid and potentially leaving the borrower owing more while the vehicle depreciates.
Another mistake is focusing entirely on the Bank of Canada rate. The central-bank policy rate influences broader financial conditions, but it is not the same as an individual consumer’s auto-loan rate. The actual offer depends on borrower and transaction characteristics.
Borrowers should also avoid submitting applications without reviewing their credit information, accepting unnecessary optional products without understanding their cost, or signing documents before confirming the complete financing arrangement.
FCAC notes that in most provinces and territories there is generally no automatic cooling-off period for car loans and lease agreements, making it especially important to understand the contract before signing.
Frequently Asked Questions
1. What is the auto loan market outlook 2026 Canada?
The auto loan market outlook 2026 Canada is being shaped by a 2.25% Bank of Canada policy rate, elevated economic uncertainty, changing vehicle demand, household debt and evolving credit risk. The Bank’s July projections anticipated economic growth of 0.7% in 2026 and 1.8% in 2027 and 2028, while inflation was projected to move toward approximately 2% in 2027. These conditions can influence lending markets, but they do not establish the rate an individual borrower will receive.
2. Will car loan rates fall in Canada in 2026?
There is no guaranteed direction for individual car-loan rates. The Bank of Canada held its policy rate at 2.25% on September 2, 2026, while noting increased inflation risks and greater uncertainty around growth. The Bank’s Q2 2026 Market Participants Survey showed a median policy-rate expectation of 2.25% for the remaining scheduled 2026 decisions, but expectations are not guarantees.
3. How do expected rate movements Canada affect borrowers?
Expected rate movements Canada can affect the broader cost of borrowing and lender funding conditions, but an individual auto-loan rate is also influenced by credit history, income, vehicle, loan amount, term and lender policy. A borrower should therefore compare actual financing offers instead of basing a purchase decision solely on expectations about future central-bank decisions.
4. Are Canadian auto-loan delinquencies increasing?
Credit stress has increased in parts of the Canadian consumer-credit market. TransUnion reported that more Canadians were seriously behind on payments year over year in Q2 2026, with notable stress in Alberta, Saskatchewan and Ontario. However, this does not mean every auto borrower or province has the same risk profile.
5. Should I wait for lower rates before buying a vehicle?
Waiting can make sense for some borrowers and may not make sense for others, depending on transportation needs, vehicle pricing, available financing and personal affordability. Rather than assuming future rates will move in one direction, compare the total cost of buying now with the realistic alternatives available to you.
6. How can I improve my chances of auto-loan approval?
Start by reviewing your Equifax and TransUnion credit reports, correcting errors, organizing income documentation, reducing unnecessary debt obligations and choosing a vehicle that fits your budget. FCAC confirms that Canadians can access their credit reports from both major credit bureaus and recommends checking reports for errors and fraud.
7. Is a longer car-loan term better because the payment is lower?
A longer term can reduce the scheduled monthly payment, but it may increase total interest and extend the period during which the borrower owes money on a depreciating vehicle. The appropriate term depends on the vehicle price, rate, payment capacity and expected ownership period. Comparing total borrowing costs is more informative than looking only at the monthly payment.
8. Where can Canadians compare auto-financing options?
Canadians can explore financing through banks, credit unions, dealerships and independent financing companies. FCAC recommends shopping around, obtaining multiple quotes where possible and comparing the total cost of borrowing before signing.
Final Outlook: What Canadian Borrowers Should Watch
The auto loan market outlook 2026 Canada points to a market where affordability, credit quality and economic uncertainty are likely to remain important alongside interest rates. The Bank of Canada’s policy rate is currently 2.25%, while the central bank continues to monitor inflation, growth, energy prices and trade developments.
Vehicle demand is also evolving. July 2026 new-vehicle unit sales were lower year over year, while dollar sales increased, and zero-emission vehicle sales continued to grow rapidly. Meanwhile, consumer debt has reached record levels and credit stress is uneven across Canada.
For borrowers, the practical response is preparation rather than prediction. Check your credit, establish a realistic budget, compare financing channels, review the complete cost of borrowing and avoid selecting a vehicle solely because the monthly payment appears affordable.
If you are ready to explore Canadian vehicle financing, QuickApprovals.ca provides an online starting point for applicants seeking financing options based on their circumstances. Review your options carefully, understand the terms and choose financing that remains manageable beyond the day you drive the vehicle home.
Suggested Internal Links for QuickApprovals.ca
- https://quickapprovals.ca/
- https://quickapprovals.ca/requirements-for-car-loan-in-canada/
- https://quickapprovals.ca/car-loan-portfolio-trends-canada/
- https://quickapprovals.ca/car-loan-default-rates-canada/
- https://quickapprovals.ca/online-car-loan-approval-process-canada/
- https://quickapprovals.ca/car-loan-term-length-guide-canada/
Suggested Authority Outbound References
- https://www.bankofcanada.ca/core-functions/monetary-policy/key-interest-rate/
- https://www.bankofcanada.ca/publications/mpr/mpr-2026-07-15/
- https://www150.statcan.gc.ca/n1/daily-quotidien/260915/dq260915c-eng.htm
- https://www.canada.ca/en/financial-consumer-agency/services/loans/financing-car.html
- https://www.canada.ca/en/financial-consumer-agency/services/credit-reports-score/order-credit-report.html
- https://www.transunion.ca/iir/reports/q2-2026