Buying an RV can turn weekends, holidays and long-distance travel into experiences you remember for years. But the purchase price of a recreational vehicle can be substantial, and paying cash is not realistic for every Canadian household. That is where recreational vehicle loans Canada can provide a structured way to finance the purchase while preserving cash for insurance, maintenance, fuel, storage and unexpected expenses.
The challenge is finding financing that fits both the vehicle and your budget rather than focusing only on the monthly payment. A motorhome, travel trailer and other recreational vehicles can have different values, useful lives and financing requirements, so the loan structure matters.
This guide explains how recreational vehicle loans Canada work, how RV auto style financing Canada may differ from conventional auto financing, what borrowers should know about motorhome car loans Canada and travel trailer financing Canada, how to compare the best RV loan rates Canada, and how to prepare an application efficiently.
What Are Recreational Vehicle Loans Canada?
Recreational vehicle loans Canada are financing arrangements used to purchase eligible recreational vehicles such as motorhomes, travel trailers and other qualifying RVs. Depending on the lender and transaction, financing may be arranged through a dealership, bank, credit union, independent finance company or financing platform. The exact eligibility rules vary because not every lender treats recreational vehicles in exactly the same way.
Some may use vehicle-focused lending products, while others may structure the transaction differently based on the RV, borrower profile, purchase price and repayment period.
The most important distinction is that an RV is more than a simple transportation purchase. A buyer may use a motorhome as both a vehicle and temporary living or travel space, while a travel trailer may require a separate tow vehicle. That means the overall financial commitment can include more than the loan payment.
Insurance, registration, storage, maintenance, campground costs, fuel and repairs can materially affect the true cost of ownership. When evaluating recreational vehicle loans Canada, therefore, borrowers should calculate the complete ownership budget before deciding how much to finance.
Canadian consumer-finance guidance recommends looking beyond the monthly payment when comparing vehicle financing. The Financial Consumer Agency of Canada advises consumers to consider the interest rate, financing fees, amount financed, payment schedule, loan term and total cost. Longer terms can reduce the required payment while increasing the amount of interest paid over time.
How RV Auto Style Financing Canada Can Work
RV auto style financing Canada describes an approach in which recreational vehicle financing is handled similarly to vehicle financing, although the precise structure depends on the lender. The borrower typically provides personal information, income details, credit information, the RV purchase information and the requested financing amount. The lender then assesses the application according to its underwriting criteria.
The process can begin before you have selected a specific RV or after you have identified one. Getting an understanding of potential financing capacity before shopping can help prevent you from choosing a recreational vehicle that stretches your budget. Once the exact RV is selected, the lender may need additional information about the vehicle, seller, purchase price, age, condition and other characteristics. A preliminary assessment should not automatically be treated as a final approval because final terms can depend on information supplied later in the process.
For federally regulated financial institutions, Canadian rules require appropriate disclosure of important borrowing information. The Financial Consumer Agency of Canada explains that borrowers should receive a disclosure statement before finalizing certain credit agreements, including information about the cost of borrowing.
Motorhome Car Loans Canada: What Borrowers Should Know
Motorhome car loans Canada can be relevant when the recreational vehicle being purchased is a motorhome rather than a towable trailer. Motorhomes can involve larger financing amounts because the vehicle combines transportation with onboard accommodation. The price can also vary considerably depending on the size, age, equipment, mileage, condition and manufacturer of the unit.
When comparing motorhome car loans Canada, do not assume that the advertised interest rate tells you the complete cost. A $70,000 motorhome financed over a long period can produce a manageable monthly payment while still generating significant interest. The borrower should compare the amount financed, rate, payment frequency, term and total repayment amount together.
It is also important to budget for costs outside the financing agreement. Insurance, fuel consumption, winter storage, maintenance, repairs and campground expenses can all affect affordability. A motorhome that appears affordable based on the loan payment alone may become considerably more expensive once operating costs are included. A responsible financing decision therefore begins with the total ownership budget rather than the maximum amount a lender is willing to finance.
Travel Trailer Financing Canada: A Different Financing Scenario
_Travel trailer financing Canada can work differently from motorhome financing because the trailer generally requires a suitable tow vehicle. The borrower therefore needs to consider two connected financial questions: the cost of the trailer itself and the ability of the existing or planned tow vehicle to safely handle it.
Before committing to travel trailer financing Canada, review the trailer’s purchase price, required down payment, financing term and expected payment. Then separately consider insurance, storage, maintenance and towing-related costs. If a different truck or SUV is required, that purchase creates another financial obligation that should be included in the household budget.
The towing relationship also matters operationally. The correct vehicle must meet the manufacturer’s towing specifications and applicable safety requirements. Financing approval does not mean a particular vehicle-and-trailer combination is appropriate for towing. The financing decision and the safe-use decision should be treated as separate considerations.
How to Compare the Best RV Loan Rates Canada
Searching for the best RV loan rates Canada requires more than finding the lowest percentage advertised online. An advertised rate may apply only to particular borrowers, vehicles, terms or lending conditions. Your personalized rate can depend on credit history, income, existing debt, loan amount, down payment, vehicle characteristics and lender policies.
A useful comparison should place competing offers on the same basis. For example, compare the same amount financed, similar repayment period and equivalent payment frequency. Then review the interest rate, financing fees and total amount repaid. A lower monthly payment is not necessarily a lower-cost loan if it results from extending the repayment period.
Canadian government guidance similarly recommends obtaining multiple financing quotes and comparing the total financing package rather than focusing only on the payment.
Illustrative RV Financing Cost Comparison
The following examples are for illustration only and are not advertised or guaranteed best RV loan rates Canada. Actual offers vary by lender and borrower.
| Amount Financed | Illustrative Rate | Term | Approx. Monthly Payment | Approx. Interest |
|---|---|---|---|---|
| $50,000 | 6.55% | 84 months | $744 | $12,469 |
| $50,000 | 8.99% | 84 months | $804 | $17,553 |
| $50,000 | 11.99% | 84 months | $882 | $24,119 |
| $80,000 | 6.55% | 120 months | $910 | $29,250 |
These examples use standard amortization calculations and exclude taxes, fees, insurance and other ownership expenses. The comparison demonstrates why the interest rate and term deserve attention. On the same $50,000 balance over 84 months, the difference between the illustrative 6.55% and 11.99% scenarios produces thousands of dollars in additional interest.
The Bank of Canada reported an average rate of 6.55% for newly advanced auto loans from the chartered banks included in its June 2026 lending-rate statistics. That figure is a market statistic for auto loans, not a guaranteed rate for recreational vehicle financing or an individual borrower.
What Determines Your Recreational Vehicle Financing Cost?
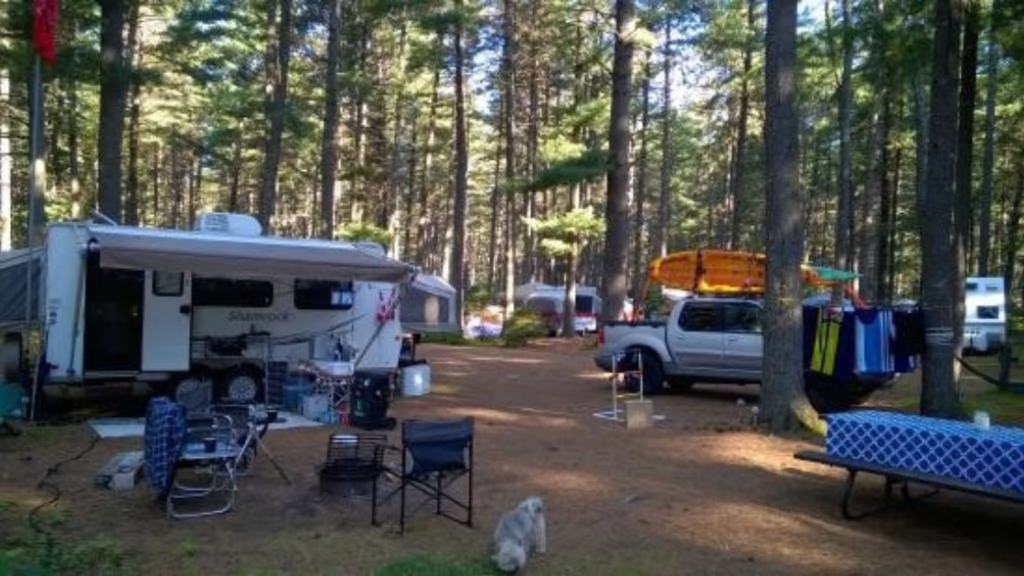
Recreational vehicle loans Canada are priced according to the lender’s assessment of the overall application. Credit history is one factor, but it is not necessarily the only factor. A lender may also review income, employment, existing debt obligations, the amount requested, down payment, vehicle information and other underwriting details.
The RV itself can also matter. A newer recreational vehicle may have different financing characteristics from an older unit. A lender may consider the purchase price, valuation, age, condition or other vehicle-specific factors when determining whether the transaction fits its lending policy.
The requested term is another major consideration. Extending a loan can reduce the payment required each month, but it generally increases the time during which interest accrues. Canadian consumer guidance specifically warns that longer vehicle-loan terms can reduce payments while increasing total interest costs.
Recreational Vehicle Loan Eligibility and Requirements
Recreational vehicle loans Canada generally require borrowers to provide enough information for the lender to assess identity, income, creditworthiness and the proposed transaction. Exact requirements differ among lenders, so there is no universal Canadian checklist that guarantees approval.
Common information requested during an application can include:
- Government-issued identification
- Residential information
- Employment details
- Income information
- Existing debt obligations
- Banking information where required
- Requested loan amount
- Down-payment information
- RV make, model and year
- Purchase price
- Seller or dealership information
- Vehicle documentation where required
Accuracy is particularly important. Information that differs between an application and supporting documents can lead to additional verification and delays. Applicants should avoid estimating information carelessly simply to complete an application faster.
Credit information can also differ between Canadian credit bureaus because lenders do not necessarily report to both bureaus in exactly the same way. TransUnion explains that lenders may report account activity to one or both Canadian credit bureaus and may update information at different times.
Step-by-Step Guide to Applying for RV Financing
Step 1: Establish Your RV Budget
Start with the total amount you can reasonably devote to the purchase rather than the maximum financing amount available. Include the expected loan payment as well as insurance, fuel, storage, maintenance and other recurring expenses. This approach helps distinguish an affordable recreational vehicle from one that merely qualifies for financing.
Step 2: Determine the Amount You Need to Finance
Calculate the purchase price, down payment and amount that will actually be borrowed. If taxes or eligible transaction costs are being financed, understand exactly how they affect the principal. A larger down payment can reduce the amount financed and therefore reduce interest costs, although the right amount depends on your broader cash-flow situation.
Step 3: Compare Financing Sources
Banks, credit unions, dealerships and independent finance companies can have different application processes and underwriting policies. The Financial Consumer Agency of Canada confirms that vehicle financing may be arranged through dealerships or directly with financial institutions, while independent finance companies can also participate in vehicle financing.
Step 4: Prepare Your Documentation
Gather identification, income information, employment details, residential information and vehicle details before submitting the application. Complete documentation can help reduce avoidable back-and-forth during underwriting.
Step 5: Review the Actual Financing Offer
Do not stop at the phrase “approved.” Review the interest rate, payment schedule, loan amount, fees, term and total cost. Ask which items are mandatory and which are optional. If additional products or services are offered, understand whether they increase the amount financed.
Step 6: Confirm the Final Agreement
Read the final financing documents carefully before signing. Confirm that the numbers match what you expected and that you understand the payment obligations. Keep copies of the completed documents for your records.
Banks vs. Lenders vs. Brokers for RV Financing
There is no single financing channel that works identically for every borrower. Each model can involve different application procedures, lender access and underwriting criteria.
| Financing Channel | Typical Characteristics | What to Compare |
|---|---|---|
| Banks | Direct relationship and established lending infrastructure | Rate, eligibility, term and total cost |
| Credit Unions | Member-based financial institutions with their own lending policies | Membership rules, rate and loan structure |
| Independent Lenders | May serve specific borrower or vehicle segments | Rate, fees, requirements and lender reputation |
| Dealership Financing | Financing can be arranged during the vehicle purchase | Multiple offers, fees and final contract |
| Brokers/Platforms | May connect applicants with financing sources | Which lenders are accessed, inquiry process and final terms |
The Financial Consumer Agency of Canada recommends comparing multiple offers and looking at the entire cost of borrowing rather than choosing solely on the basis of the monthly payment.
Practical Canadian RV Financing Examples
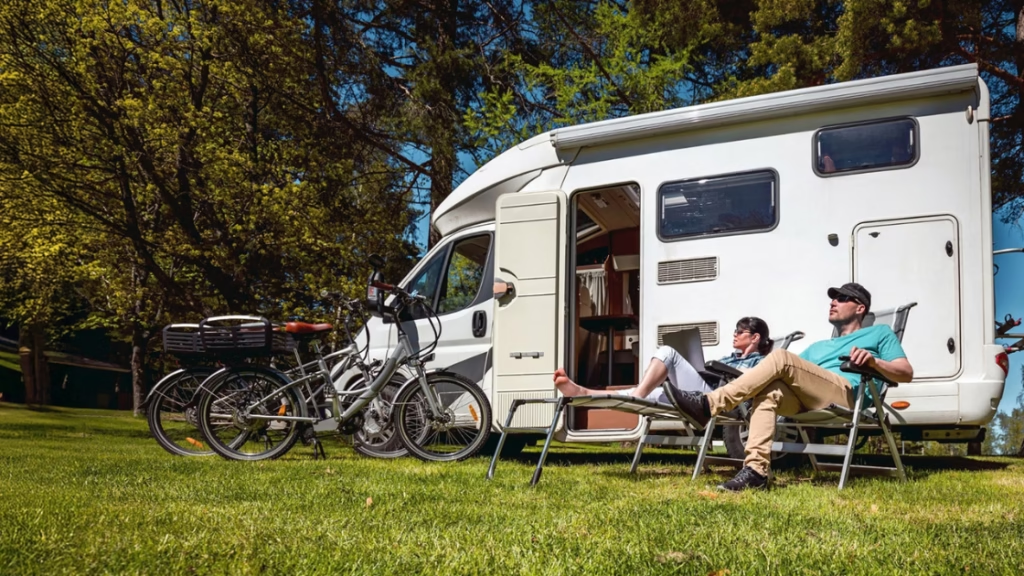
Case Study 1: $50,000 Travel Trailer
Consider a Canadian household purchasing a $50,000 travel trailer and financing the full amount for illustration. At an illustrative 6.55% rate over 84 months, the payment is approximately $744 per month and total interest is approximately $12,469. At 11.99% over the same period, the payment rises to approximately $882 and total interest rises to approximately $24,119.
The difference is important because the higher-rate scenario costs roughly $11,650 more in interest over the same seven-year period. The example demonstrates why comparing financing offers before finalizing the purchase can matter substantially.
Case Study 2: Larger Motorhome Purchase
Suppose a buyer considers financing $80,000 over 120 months at an illustrative 6.55% rate. The estimated payment is approximately $910 per month, but total interest would be roughly $29,250 before other costs. The longer term reduces the monthly obligation compared with a shorter repayment period, but the borrower pays interest for a much longer time.
This is why a payment that fits today’s budget should not automatically be treated as evidence that the financing is inexpensive. Buyers should consider how long they expect to keep the motorhome and whether the financing balance could remain significant as the RV ages.
Expert Approval Acceleration Tips
Recreational vehicle loans Canada applications can often move more efficiently when borrowers eliminate avoidable delays. The goal should not be to pressure a lender into approving an unsuitable application; it should be to make accurate information available promptly.
Start by checking your application information before submitting it. Ensure your name, address, employment information and income details are consistent with your supporting documentation. Have the RV’s purchase information ready and respond promptly if the lender requests clarification.
It can also help to understand your credit position before applying. Reviewing your credit information may allow you to identify inaccurate information that should be disputed before a major financing application. TransUnion provides Canadian consumers with information about accessing their credit report and explains how credit-report information is used by lenders.
Finally, avoid selecting a recreational vehicle solely because the lender is willing to finance it. Approval capacity and comfortable affordability are not the same thing.
Critical Mistakes to Avoid
Focusing Only on the Monthly Payment
A low payment can be created by extending the term. Always calculate the total amount repaid and total interest.
Assuming an Advertised Rate Is Guaranteed
Published rates may apply to specific circumstances. Ask for the rate and terms applicable to your actual application.
Ignoring RV Ownership Costs
Insurance, fuel, storage, repairs and maintenance can materially change the monthly ownership budget.
Financing More Than Necessary
Optional products and additional costs can increase the amount borrowed. Review every item before agreeing to finance it.
Choosing a Long Term Without Understanding the Cost
Longer repayment periods can make payments easier to manage but may increase total interest substantially.
Treating Preliminary Approval as Final Approval
A preliminary assessment can change when the lender verifies income, credit, vehicle information and other details. Read the final offer rather than relying on an earlier estimate.
Failing to Read the Disclosure
Canadian consumer guidance emphasizes reviewing the disclosure statement and understanding the total cost of borrowing before signing.
Frequently Asked Questions About Recreational Vehicle Loans Canada
Can I get recreational vehicle loans Canada for a used RV?
Recreational vehicle loans Canada may be available for used recreational vehicles, but eligibility depends on the lender and the specific RV. Age, condition, purchase price, valuation and borrower qualifications can affect whether financing is available and what terms are offered. Before choosing a used RV, ask the financing provider whether it has restrictions relating to vehicle age or type. You should also budget for potential maintenance because an older recreational vehicle may require more repairs than a newer one.
Are motorhome car loans Canada the same as ordinary car loans?
Motorhome car loans Canada may use a vehicle-financing structure, but a motorhome is not necessarily treated identically to an ordinary passenger car by every lender. The financing amount, vehicle characteristics, loan term and underwriting requirements can differ. A motorhome also has different ownership expenses, including potentially higher insurance, fuel and maintenance costs. Compare the complete financing agreement rather than assuming a standard car-loan rate or term will automatically apply.
How does travel trailer financing Canada work?
Travel trailer financing Canada generally involves financing the trailer purchase under terms determined by the lender. The borrower may need to provide information about the trailer, purchase price and seller, along with personal, income and credit information. Remember that the trailer is only part of the financial picture. You may also need a suitable tow vehicle, insurance, storage and maintenance. Those costs should be considered before determining the amount you can comfortably finance.
How can I find the best RV loan rates Canada?
To compare the best RV loan rates Canada, obtain actual financing offers and compare them using the same amount and term whenever possible. Look at the interest rate, payment frequency, fees, total interest and total amount repaid. Do not assume that the lowest advertised rate is automatically available to every applicant. Canadian consumer guidance recommends comparing multiple offers and evaluating the complete cost of financing rather than focusing exclusively on the monthly payment.
Can bad credit affect recreational vehicle loans Canada?
Credit history can affect the financing options and terms available to a borrower, although lenders may consider other factors as well. Income, existing debt, down payment, vehicle characteristics and overall application strength can influence underwriting. If your credit history contains errors, correcting them before applying may be worthwhile. A borrower should also be cautious about accepting a substantially more expensive loan simply because it is available quickly.
Does a longer RV loan term reduce my total cost?
Usually, extending the term lowers the scheduled payment but increases the period over which interest is charged. The Canadian government gives the same general warning for vehicle financing: longer terms can reduce payments while increasing the total interest paid. The correct term depends on your budget and financial objectives, but it should be selected after comparing total repayment costs rather than payment size alone.
Should I get financing before choosing an RV?
Obtaining an understanding of your financing position before shopping can help establish a realistic purchase budget. However, preliminary financing information is not necessarily final approval. Once you choose the recreational vehicle, the lender may need to verify its details, purchase price and eligibility. Getting financing information early can therefore help with budgeting while still leaving room for final underwriting after the RV is selected.
What should I check before signing an RV loan?
Before signing, review the amount financed, interest rate, payment schedule, term, fees, total cost and any optional products included in the agreement. Confirm that the final figures match your expectations. Ask questions about anything you do not understand and keep a copy of the completed documents. The Financial Consumer Agency of Canada specifically advises consumers to carefully review financing disclosures before finalizing a vehicle-financing agreement.
Final Thoughts on Recreational Vehicle Loans Canada
Choosing recreational vehicle loans Canada should be about more than securing approval for an RV. The financing needs to make sense alongside the purchase price, repayment period, interest cost and ongoing expenses of ownership. Whether you are researching RV auto style financing Canada, motorhome car loans Canada, travel trailer financing Canada or comparing the best RV loan rates Canada, the same principle applies: compare the complete financing package rather than choosing based on one attractive number.
Before signing, know how much you are borrowing, what interest rate applies, how long repayment will take, what fees are included and how much you will repay in total. Check your credit information, prepare accurate documentation and compare available financing channels. Most importantly, build the RV payment into a realistic household budget that also accounts for insurance, fuel, storage, maintenance and other ownership expenses.
If you are ready to explore recreational vehicle loans Canada, Quick Approvals can provide an online starting point for Canadian vehicle financing. Explore Quick Approvals Compare your options carefully, understand the final agreement and choose financing that fits the recreational vehicle you want as well as the financial commitments you can comfortably manage.
Internal Links for Quick Approvals
- Recreational Vehicle Loans Canada
- RV Auto Style Financing Canada
- Motorhome Car Loans Canada
- Travel Trailer Financing Canada
- Best RV Loan Rates Canada
- RV Loan Approval Requirements Canada
Authority Outbound References
- Financial Consumer Agency of Canada — Car Financing Options
- Financial Consumer Agency of Canada — Shopping Around for Auto-Financing
- Financial Consumer Agency of Canada — Consumer Protection When Buying a Car
- Financial Consumer Agency of Canada — Cost of Borrowing Regulations
- TransUnion Canada — Credit Reports
- Government of Canada — Personal Loans and Total Borrowing Cost